A car repossession does not automatically end your chances of buying a house in Atlanta. But with Atlanta's median home sale price at $427,467 in August 2026, getting your credit file mortgage-ready before applying matters.
A repossession can remain on your credit report for seven years from the original delinquency that led to the default. Mortgage lenders also evaluate your current credit score, debt-to-income ratio, payment history, and whether the repossession left an unpaid deficiency balance.
If you want to buy a house in Atlanta after a car repossession, start by checking the repo's balance and reporting accuracy.
Then review your current score, monthly debt, and the positive payment history you have built since the repossession.
Can You Buy a House in Atlanta After a Car Repossession?
Yes. A car repossession does not automatically prevent you from buying a house in Atlanta. What matters now is the condition of your credit file, including your current score, payment history, debt-to-income ratio, and any unpaid deficiency balance from the repossession.
Before applying for a mortgage, use the steps below to identify what needs attention first.
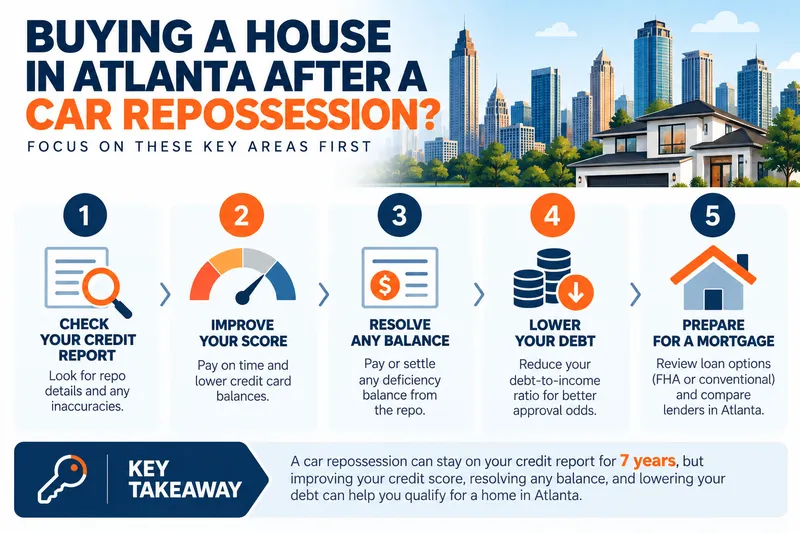
A car repossession does not close the door on buying a house in Atlanta. FHA has no mandatory waiting period after a repo, and conventional lenders generally want 24 months of clean payment history since it happened. What actually decides approval is your current score, your debt-to-income ratio, and whether the repossession left an unpaid balance still sitting in collections. This article answers the real questions Atlanta buyers are asking in forums and comment sections right now, with current 2026 data.
Does a Repossession Stop You From Getting a Mortgage in Atlanta?
No. A repossession alone does not block a mortgage. FHA has no mandatory waiting period after a repo, and conventional lenders typically want about 24 months of clean payment history since it happened. The bigger obstacle is usually an unpaid deficiency balance still sitting in collections.
This is the question that shows up again and again in real buyer forums, and it is worth taking seriously because a lot of the advice circulating online is outdated. A thread on the myFICO Forums repossession and approval discussion is a good snapshot of how lenders and experienced borrowers actually think about this. The consensus among posters, including people who work in lending, is that a paid auto repossession carries much less weight than people assume, because roughly 9 out of 10 conventional approvals run through automated, GSE-validated underwriting rather than a manual file review. A car repo does not automatically trigger the kind of manual scrutiny that a foreclosure or bankruptcy does.
That said, not disqualifying is different from invisible. A repossession still drags your score down, and it still shows up as a derogatory mark for years. The real question that determines your timeline is whether you have paid off any remaining balance and rebuilt your score to your loan program's floor.
How Long Does a Repossession Stay on Your Credit Report?
Seven years, counted from the date of the original missed payment that led to the default, not the date the car was actually taken. This is set by the Fair Credit Reporting Act and applies whether the loan ended in voluntary surrender or involuntary repossession.
According to Experian's guidance on mortgages after a vehicle repossession, the seven-year clock starts when your account first went delinquent and was never brought current again, not when the vehicle itself was repossessed. That distinction matters, because it means the repossession is often closer to falling off your report than the repo date alone would suggest.
| Factor | What It Means for You |
|---|---|
| Time on credit report | 7 years from first missed payment, per FCRA |
| Typical score impact | Drop of roughly 100 to 150 points at the time of repossession |
| Deficiency balance | Reports separately as a collection account until paid or settled |
| Score recovery | Gradual, and accelerates once the balance is resolved and new positive history builds |
Still Carrying an Old Repo on Your Report?
A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion currently report, including whether a deficiency balance is still active, before you apply for a mortgage.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Credit Score Do You Need to Buy a House in Atlanta After a Repo?
FHA loans generally require a minimum 580 score for 3.5% down, or 500 to 579 with 10% down. Conventional loans generally require a minimum 620. Some lenders add their own stricter overlays on top of these baseline numbers, especially after a recent derogatory mark like a repossession.
One nuance worth knowing: Fannie Mae updated its automated underwriting system in November 2025, moving away from a hard 620 cutoff toward a more flexible, risk-based assessment through Desktop Underwriter. In practice, a small number of borrowers below 620 can still get an automated approval if the rest of the file is strong. That does not mean 620 has stopped mattering. Most lenders in the Atlanta market still treat it as their practical floor for conventional loans, so it remains the number to plan around.
What Matters More Than the Repo Itself?
Underwriters weigh three things above the repossession itself: your current credit score, your debt-to-income ratio, and whether the account still shows an unpaid balance. Resolving the deficiency balance is usually the single biggest lever you control.
- ✓ Pay off or settle any deficiency balance from the repossession before applying
- ✓ Wait until you meet your loan program's minimum score, not just any score
- ✓ Build 12 to 24 months of on-time payments on other accounts since the repo
- ✓ Keep your debt-to-income ratio below your lender's threshold, typically 43 to 50 percent
- ✓ Shop more than one lender, since overlays on repo history vary
Most underwriters require this resolved before closing. This is the single most common reason a repo actually blocks approval.
Still visible for up to seven years, but carries much less weight in an automated underwriting decision.
What Is the Atlanta Housing Market Doing Right Now?
Atlanta's median home sale price was $427,467 in August 2026, up 9.1 percent year over year, with homes typically spending 57 days on market. That pace gives buyers rebuilding their credit after a repo more breathing room than a fast-moving seller's market would.
According to Redfin's Atlanta housing market data, prices are climbing but the market is not moving so fast that a buyer needs to rush before their credit is ready. Fifty-seven days on market means there is real room to spend a few more months paying down a deficiency balance or rebuilding score before making an offer, without losing meaningful ground on price.
What If the Repossession Was Reported Incorrectly?
If the repossession balance, dates, or account status are inaccurate, you have the right under the Fair Credit Reporting Act to dispute it directly with the credit bureau and require the furnisher to verify the information within 30 days or remove it.
Not every repossession on a credit report is reported correctly. Wrong balances, duplicate tradelines from the original lender and a debt collector, or an incorrect delinquency date are common enough that they are worth checking before assuming the mark is accurate and permanent.
A car repossession does not close the door on homeownership in Atlanta. It is a setback, not a disqualifier. The path forward is straightforward: resolve any unpaid balance, hit your loan program's minimum score, and give your file 12 to 24 months of clean history. Atlanta's current market pace gives you room to do that before you need to compete for a home.
Can you buy a house in Atlanta after a car repossession?
Yes. A car repossession does not disqualify you from an FHA or conventional mortgage in Atlanta. FHA has no mandatory waiting period after a repossession, and conventional lenders typically want 24 months of clean payment history since it happened. What matters most is your current credit score, your debt-to-income ratio, and whether any deficiency balance from the repossession is still unpaid.
How long does a car repossession stay on your credit report?
A repossession stays on your credit report for seven years, counted from the date of the original missed payment that led to the default, not from the date the car was repossessed. This is set by the Fair Credit Reporting Act.
Do mortgage lenders care about a repossessed car?
Mortgage underwriters mainly evaluate your current score, your debt-to-income ratio, and mortgage-specific credit behavior. A paid repossession with no remaining balance carries much less weight than an open, unpaid deficiency balance, which reports as an active collection account and can block approval.
What credit score do you need to buy a house in Atlanta after a repo?
FHA loans typically require a minimum 580 score for 3.5% down, or 500 to 579 with 10% down. Conventional loans generally require a minimum 620. Individual lenders can set higher overlays after a repossession, so shopping more than one lender matters.
Should I pay off a repossession deficiency balance before applying for a mortgage?
Yes, in almost every case. An unpaid deficiency balance shows up as an open collection account, which most underwriters require to be paid or resolved before closing. Paying it also removes one of the biggest weights on your credit score.
Find Out Exactly What's Holding Your Score Back
Get a free, no-obligation credit analysis and a clear plan to get mortgage-ready after a repossession, backed by a full 3-bureau review.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
Can You Buy a House With a Repo on Your Credit? Breaks down FHA and conventional score minimums and waiting periods after a repossession, step by step.
-
How To Get a Repo Off Your Credit: Proven Strategies That Work Covers dispute strategy and documentation for removing an inaccurately reported repossession.
-
Car Loan After Repossession: Complete Recovery Guide Explains how to rebuild auto credit after a repossession, useful context before tackling a mortgage.
-
Can You Remove a Repo From Your Credit Report? Yes, Here's How A real client case showing how FCRA documentation requirements led to a 102-point score improvement.