People searching for trusted credit repair companies in New York should evaluate more than rankings, testimonials, or promises of a higher score. A credible search starts with verifiable business information, transparent pricing, written service terms, consumer rights, and a clear explanation of what a credit repair company can and cannot legally do.
That distinction matters because credit repair has defined legal limits. The Consumer Financial Protection Bureau states that accurate, current negative information generally cannot be removed simply because it hurts a credit score. Consumers also have the right to dispute inaccurate information directly with credit reporting companies and data furnishers at no cost. Most negative account information can generally remain on a credit report for up to seven years.
For New Yorkers comparing providers, claims of guaranteed score increases, instant deletions, or removal of accurate negative records should therefore trigger closer scrutiny. The CFPB also identifies demands for payment before promised services are completed as a warning sign.
What New Yorkers Look for Before Choosing Credit Repair Help
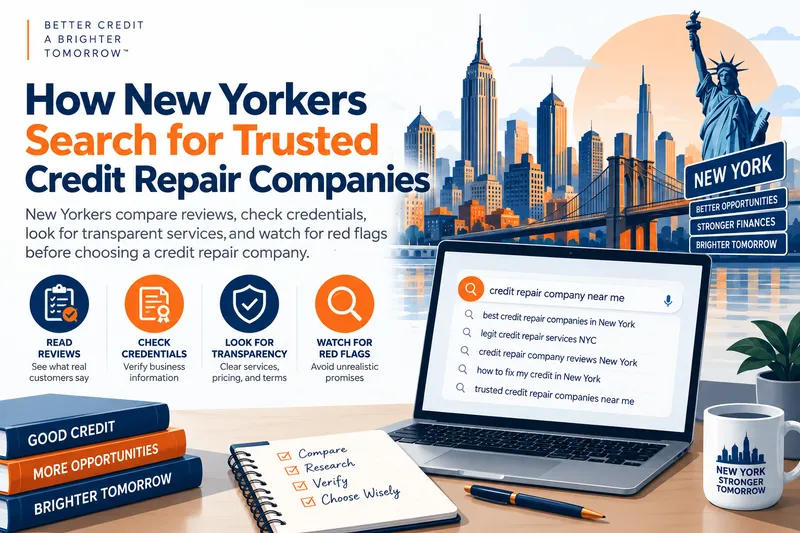
Choosing a credit repair company starts with verifying what is behind its claims. New York consumers can compare independent customer feedback, review pricing and service terms, confirm business information, and examine whether a provider clearly explains the credit dispute process.
Transparency is especially important when a company promises results. Credit repair cannot guarantee the deletion of accurate negative information or a specific increase in a credit score. Providers should instead explain what they review, which information may qualify for a dispute, what the service costs, and what rights consumers retain throughout the process.
The factors below provide a practical framework for researching and comparing credit repair companies before signing an agreement.
Checklist for Comparing Credit Repair Companies
Before paying for credit repair, compare providers using the same criteria rather than relying on one review, advertisement, or promised outcome. Use this checklist to document what each company actually offers.
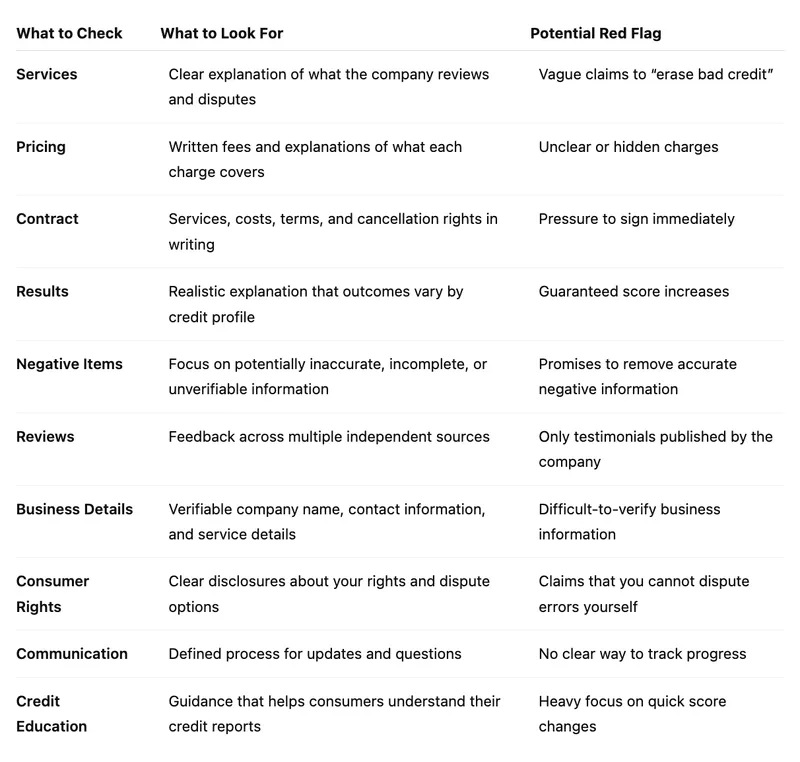
No single factor proves that a credit repair company is trustworthy.
Look for consistency across its contract, pricing, claims, business information, reviews, and dispute practices. Comparing several providers against the same checklist makes it easier to identify meaningful differences before committing to a paid service.
New Yorkers do not pick a credit repair company the way they pick a coffee shop. Before handing over a credit report, most people search BBB profiles, check state law, and read every review they can find, because a bad choice can cost real money and do nothing for their score. New York backs that caution up with one of the stricter state laws in the country, General Business Law Article 28-BB, which bans advance fees outright. This article breaks down exactly how careful New Yorkers vet a credit repair company, what the law actually requires, and why credit scores swing so widely from one New York City neighborhood to the next.
How Do New Yorkers Search for a Trustworthy Credit Repair Company?
New Yorkers vet a trustworthy credit repair company by checking its BBB profile and complaint history, confirming it never asks for payment upfront, reading its contract terms before signing, and verifying it follows New York's Credit Services Business law. Searching the company name alongside terms like "complaints" or "lawsuit" is also common before committing.
New York consumers tend to run through a short mental checklist before trusting a credit repair company with their financial information. Most of that checklist comes down to a few repeatable steps.
- ✓ Search the company's Better Business Bureau profile for accreditation, star rating, and unresolved complaints
- ✓ Confirm the company does not ask for a fee before completing any work
- ✓ Read the full written contract, including cancellation terms, before signing anything
- ✓ Search the company name with terms like "complaint," "lawsuit," or "scam" to surface anything not on the BBB profile
- ✓ Check how long the company has operated and whether it has a real, findable business address
- ✓ Compare pricing models, since flat-fee and per-deletion pricing are easier to evaluate than open-ended monthly billing
The Better Business Bureau's own guidance on credit repair and debt relief services reinforces the same pattern nationally. It tells consumers to check a company's BBB review before paying anything, and it lists paying fees before debts are settled as one of the clearest signs of a predatory operator.
What Does New York Law Require of Credit Repair Companies?
New York General Business Law Article 28-BB, the Credit Services Business law, requires a written contract with specific disclosures, bans advance fees under Section 458-E, and prohibits deceptive practices under Section 458-H. Consumers can sue for damages under the law, and the New York Attorney General can enforce it directly against violators.
New York does not leave credit repair oversight to chance. General Business Law Article 28-BB lays out specific rules a credit services business has to follow in the state, and the sections build on each other from disclosure through enforcement.
| Section | What It Covers | Why It Matters to You |
|---|---|---|
| 458-C, 458-D | Required consumer information statement before signing | You must be told your rights before any agreement is made |
| 458-E | Advance fees prohibited | No legitimate company can collect payment before doing the work |
| 458-F, 458-G | Contract requirements, and when a contract is void | A contract missing required terms may not be enforceable at all |
| 458-H | Deceptive acts prohibited | Bans false claims about what the company can guarantee |
| 458-I, 458-J | Civil damages and Attorney General enforcement | You have a legal path if a company violates the law |
Why Do Credit Scores Vary So Much Across New York City Boroughs?
Credit scores across New York City track closely with income and neighborhood, according to an Experian analysis. The Upper East and Upper West Side averaged 746, while the Central Bronx averaged 641, an 81-point spread within the same city. Manhattan led all boroughs at 714, followed by Queens, Staten Island, Brooklyn, and the Bronx.
That gap is not random. Access to traditional credit, income levels, and how many accounts show up on a credit file all move together. A person with fewer open accounts and less credit history available to lenders tends to score lower, even with a clean payment record, which is part of why how a credit score is actually calculated matters just as much as paying bills on time.
What Red Flags Should New Yorkers Watch for When Comparing Companies?
Watch for any company that asks for payment before starting work, promises a guaranteed score increase, claims it can remove accurate negative information, or tells you to stop contacting your creditors. All four practices violate New York law and are consistent warning signs across the industry.
Upfront fees, guaranteed point increases, promises to remove accurate items, pressure to sign same-day, and no verifiable business address.
Fees only after work is done, a written contract with cancellation terms, a real BBB history, and a straight answer when asked about guarantees.
Comparing a few options side by side before committing is worth the extra time. A useful next step is reading how to choose the right credit repair company, which walks through pricing structures, contract flexibility, and how to weigh reviews against a company's actual dispute process.
A flashy website does not make a company trustworthy, and neither does a low price by itself. What matters is whether the company follows New York law, tells you the truth about what it can and cannot guarantee, and lets you see your own credit file before asking you to commit to anything.
How Does ASAP Credit Repair Approach Trust With New York Clients?
ASAP Credit Repair has operated since 1998 and served more than 22,000 clients nationwide, including New York residents, under CROA registration. The company uses flat-fee pricing instead of open-ended monthly billing and starts every relationship with a free 3-bureau credit review before any work begins.
New York's advance-fee ban and disclosure requirements are not obstacles to work around. They are close to how ASAP already operates. Every review starts with pulling the actual credit file from Equifax, Experian, and TransUnion, so a client can see exactly what is being disputed before agreeing to anything, a habit worth building regardless of which company someone eventually chooses, as covered in how to check your credit score correctly.
New Yorkers research credit repair companies carefully, and the law backs that instinct with real protections, including a full ban on advance fees. Credit scores vary sharply across the city's boroughs, often tied to income and credit access rather than missed payments alone. The same checklist that works for evaluating any company, checking fees, contracts, and complaint history, applies whether someone is comparing options or already leaning toward one.
How can I tell if a credit repair company in New York is trustworthy?
A trustworthy New York credit repair company does not charge you before completing any work, gives you a written contract, and never promises a guaranteed score increase. Check its BBB profile for accreditation and complaint history, and confirm it follows New York General Business Law Article 28-BB, which bans advance fees and requires clear written contracts.
What does New York law require of credit repair companies?
New York General Business Law Article 28-BB, the Credit Services Business law, requires a written contract with specific disclosures, bans collecting fees before services are delivered under Section 458-E, and prohibits deceptive acts under Section 458-H. Consumers can sue for damages, and the Attorney General can enforce the law directly.
Is it legal for a credit repair company to charge fees before doing the work in New York?
No. Section 458-E of New York General Business Law Article 28-BB prohibits credit repair and credit services businesses from collecting any payment until the promised services are actually completed. A company asking for money upfront in New York is violating state law, not just showing a red flag.
Why do credit scores vary so much across New York City boroughs?
Credit scores across New York City track closely with income and access to credit. An Experian neighborhood analysis found the Upper East Side and Upper West Side averaging 746, while parts of the Central Bronx averaged 641, an 81-point gap between the highest and lowest scoring areas of the city.
What red flags should I watch for when comparing credit repair companies in NYC?
Watch for any company that asks for payment before starting work, guarantees a specific score increase, promises to remove accurate negative information, or tells you to stop communicating with creditors. These practices violate New York law and are consistent signs of an untrustworthy operator.
See Your Full Credit File Before You Trust Anyone With It
A free 3-bureau review shows exactly what Equifax, Experian, and TransUnion currently report, so you can compare that against any company's claims before agreeing to a single dollar.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
Are Credit Repair Companies Fraud? How to Spot a Legit Service Explains why some credit repair companies earn a bad reputation and what actually separates a legitimate operator from a scam.
-
Choosing the Right Credit Repair Company: Expert Tips Walks through pricing models, reviews, and contract terms to check before signing with any credit repair company.
-
How Is a Credit Score Calculated? The 5 Factors FICO Uses Breaks down payment history, utilization, and the other factors behind every FICO score, including why New York City scores vary so widely.
-
How to Effectively Check Your Credit Score and Why It Matters Covers how to pull your own credit report correctly before comparing it against any company's dispute claims.
-
BBB: Credit Repair and Debt Relief Services Guide The Better Business Bureau's own guidance on researching and vetting credit repair and debt relief companies before paying anything.
-
New York General Business Law Article 28-BB: Credit Services Business The full text of New York's Credit Services Business law, including the advance fee ban and contract requirements.
-
WalletHub: States With the Highest and Lowest Credit Scores WalletHub's 2026 state-by-state credit score ranking, including New York's position relative to the national average.