A 620 credit score does not automatically put an Orlando home out of reach. But before applying for a mortgage, the bigger question is what is keeping the score at 620 and whether fixing it could improve the loan terms.
That matters in Orlando's current housing market. The median home price was $400,676 in August 2026, according to the Orlando Regional REALTOR® Association, while the area's reported mortgage rate was about 6.7%. At that price level, even a relatively small difference in borrowing costs can affect a buyer's monthly payment and purchasing power.
A 620 score may also leave more than one mortgage path open. FHA policy permits scores of 580 and above under its standard maximum-financing rules, although lenders can apply additional underwriting requirements.
“If someone comes to us at 620 and wants to buy a house, I would not focus on the number alone,”
“I would look at what is creating that number: high card balances, recent late payments, collections, or inaccurate information.”
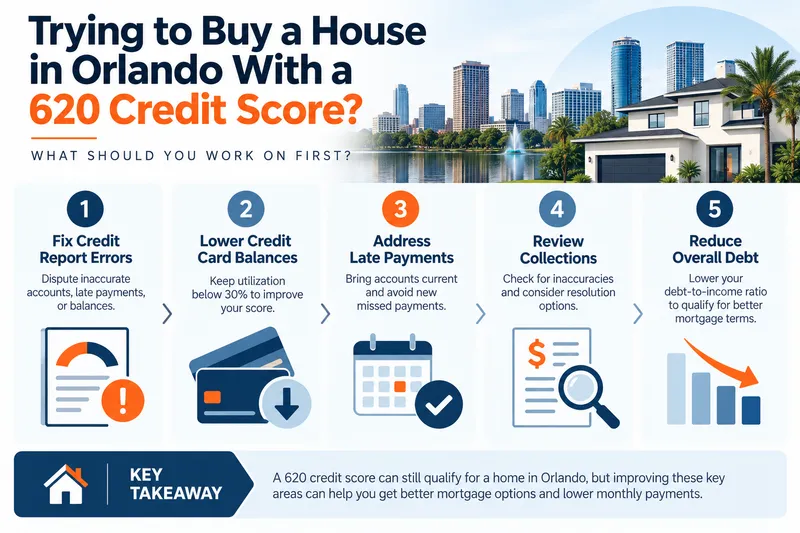
So, if you're trying to buy a house in Orlando with a 620 credit score, work first on the credit factors that can realistically change before you apply, while also reviewing debt, cash reserves, and the mortgage programs you may qualify for.
Trying to Buy a House in Orlando With a 620 Credit Score
What Should You Work on First?
If you have a 620 credit score and want to buy a house in Orlando, start by checking what is pulling your score down. High credit card utilization, recent late payments, inaccurate negative accounts, collections, and overall monthly debt can affect mortgage readiness. Do not focus only on reaching a higher score. Your income, debt-to-income ratio, down payment, cash reserves, and mortgage program also affect whether you qualify and what the loan will cost.
A 620 credit score clears the minimum bar for both FHA and conventional financing in Orlando, so approval is not the real question. The real question is what a 620 costs versus what a few weeks of targeted work could save. This analysis breaks down Orlando's current housing numbers, the exact rate gap a 620 score carries, and the specific score threshold worth targeting before you make an offer.
Can You Actually Buy a House in Orlando With a 620 Credit Score?
Yes. A 620 score meets the typical minimum for a conventional loan and comfortably clears the 580 minimum for an FHA loan. Approval is realistic at 620, but the interest rate will be noticeably higher than what a borrower in the mid-700s receives, and a 620 score falls just short of several Florida down payment assistance programs that require 640.
| Loan Type | Minimum Score | Where a 620 Stands |
|---|---|---|
| FHA (3.5% down) | 580 | 40 points above minimum |
| Conventional | 620 (typical lender floor) | Meets the floor, but not the best-pricing tier |
| FL Hometown Heroes (DPA) | 640 | 20 points below eligibility |
What Does a 620 Score Actually Cost on an Orlando Mortgage?
At Orlando's August 2026 median home price of $400,676, a 620 score carries a 30-year conventional rate of about 7.61 percent, compared to 6.85 percent for a 780+ score. On a typical loan amount at that price point, the rate difference adds roughly $195 to the monthly payment and more than $70,000 in total interest over the life of the loan.
| Credit Score | Est. Rate | Est. Monthly Payment* | Est. Total 30-Yr Interest* |
|---|---|---|---|
| 620 | 7.61% | ~$2,686 | ~$586,900 |
| 700 | 7.14% | ~$2,566 | ~$544,600 |
| 780+ | 6.85% | ~$2,490 | ~$516,200 |
Find Out What's Keeping Your Score at 620
A free 3-bureau review shows exactly which accounts are holding your score back, so you know what to fix before locking in an Orlando mortgage rate.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Should You Work on First?
Start with credit utilization, since it is the fastest-moving factor in a mortgage score, followed by disputing any inaccurate late payments or collections, since both carry outsized weight in mortgage-specific scoring models. Crossing the 640 threshold specifically opens access to Florida's Hometown Heroes down payment assistance program, which a 620 score does not yet qualify for.
Not every fix moves a mortgage score at the same speed. Based on case data from credit repair clients working from a 620 starting point, some actions produce measurably faster results than others.
| Priority | Action | Typical Impact |
|---|---|---|
| 1 | Lower credit card utilization below 30% | Average +32 points |
| 2 | Dispute inaccurate late payments | Average +43 points when successful |
| 3 | Correct major credit report errors | Average +52 points for major errors |
| 4 | Pay small collections under $100 | Average +18 points |
| 5 | Add an authorized-user tradeline | Average +27 points |
Any single item on that list can be enough to cross from 620 into the 640 range, which matters specifically in Florida. The Hometown Heroes Housing Program offers up to $35,000 in down payment and closing cost assistance for eligible frontline workers, but requires a minimum 640 score, twenty points above where a 620 borrower currently stands.
Approved, but at 7.61% and locked out of Florida's largest down payment assistance program.
Meaningfully lower rate tier, plus eligibility for up to $35,000 in Hometown Heroes assistance.
Is Now a Good Time to Buy in Orlando With a 620 Score?
Orlando's housing inventory has climbed to roughly 4.1 months of supply with homes averaging 62 days on market, a meaningfully more buyer-friendly market than the bidding wars of recent years. That slower pace gives a 620-score buyer real room to spend 30 to 60 days improving credit before making an offer, without losing significant ground to competing buyers.
Timing works in favor of improving credit first. Orlando is not the fast-moving seller's market it was a few years ago, and both sales and new listings pulled back further in August 2026, according to the Orlando Regional Realtor Association. A 60-day credit improvement window costs a buyer very little competitive ground in a market moving this slowly, and the payoff, a meaningfully lower rate or access to DPA funds, is proportionally larger.
- ✓ Pull your full credit report and identify the fastest-moving factor, usually utilization
- ✓ Dispute any inaccurate late payment or collection before applying
- ✓ Check whether crossing 640 opens Hometown Heroes or another Florida DPA program
- ✓ Get pre-approved at your current score to know your real starting rate
- ✓ Reassess after 30 days, since Orlando's current inventory gives buyers room to wait
A 620 score is not a wall in Orlando's current market. It is a specific, closeable 20-point gap between the rate and assistance you have access to today and the rate and assistance available at 640, and Orlando's slower-moving inventory gives most buyers enough time to close it before making an offer.
A 620 credit score qualifies for both FHA and conventional financing in Orlando, at a median home price of $400,676 as of August 2026. The real cost sits in the 0.76-point rate spread between 620 and top-tier credit, worth roughly $195 a month, and in the 20-point gap standing between a 620 score and Florida's Hometown Heroes down payment assistance. With inventory at 4.1 months and homes averaging 62 days on market, most buyers have real room to close that gap before locking in a rate.
Can you buy a house in Orlando with a 620 credit score?
Yes. A 620 score meets the typical minimum for a conventional loan and comfortably clears the 580 minimum for an FHA loan. Approval is realistic at 620, but the interest rate will be noticeably higher than what a borrower in the mid-700s receives, and a 620 score falls just short of several Florida down payment assistance programs that require 640.
What should you work on first with a 620 credit score before buying in Orlando?
Start with credit utilization, since it is the fastest-moving factor in a mortgage score, followed by disputing any inaccurate late payments or collections, since both carry outsized weight in mortgage-specific scoring models. Crossing the 640 threshold specifically opens access to Florida's Hometown Heroes down payment assistance program, which a 620 score does not yet qualify for.
How much does a 620 credit score cost on an Orlando mortgage?
At Orlando's August 2026 median home price of $400,676, a 620 score carries a 30-year conventional rate of about 7.61 percent, compared to 6.85 percent for a 780+ score. On a typical loan amount at that price point, the rate difference adds roughly $195 to the monthly payment and more than $70,000 in total interest over the life of the loan.
What credit score do you need for Florida's Hometown Heroes program?
Florida's Hometown Heroes Housing Program requires a minimum credit score of 640, twenty points above a 620 score. The program offers up to $35,000 in down payment and closing cost assistance as a 0% interest, deferred second mortgage for eligible frontline workers buying their first home in Florida.
Is now a good time to buy in Orlando with a 620 credit score?
Orlando's housing inventory has climbed to roughly 4.1 months of supply with homes averaging 62 days on market, a meaningfully more buyer-friendly market than the bidding wars of recent years. That slower pace gives a 620-score buyer real room to spend 30 to 60 days improving credit before making an offer, without losing significant ground to competing buyers.
Close the Gap Between 620 and a Better Rate
A free 3-bureau audit shows exactly how close you are to a better mortgage rate tier or DPA eligibility, so you can decide whether to buy now or spend 30 days improving your file first.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
What Credit Score Do I Need for a Mortgage? Requirements & Expert Tips Breaks down minimum score requirements across FHA, conventional, VA, and USDA loans.
-
How to Buy a Home With a Low Credit Score: 7 Proven Tips Covers loan alternatives, down payment strategy, and lender options for buyers below prime credit tiers.
-
What Credit Score Do You Need for a $400,000 House? Runs the exact numbers on a $400,000 home purchase across multiple credit score tiers, close to Orlando's current median.
-
How to Increase Your 620 Credit Score in 30 Days A data-backed action plan for the fastest score-moving strategies from a 620 starting point.
-
Orlando Regional Realtor Association: Housing Market Narrative The official monthly source for Orlando median home prices, inventory, and days on market.
-
Experian: Average Mortgage Rates by Credit Score Current 30-year conventional mortgage rate data broken down by FICO score tier.
-
Florida Hometown Heroes Housing Program Official details on eligibility, credit score requirements, and assistance amounts for Florida's frontline-worker DPA program.