FHA loan collection accounts raise an expensive question for homebuyers.
Should you use money saved for closing to pay old debts before applying?
Before sending a collector anything, find out whether that payment actually addresses a mortgage requirement.
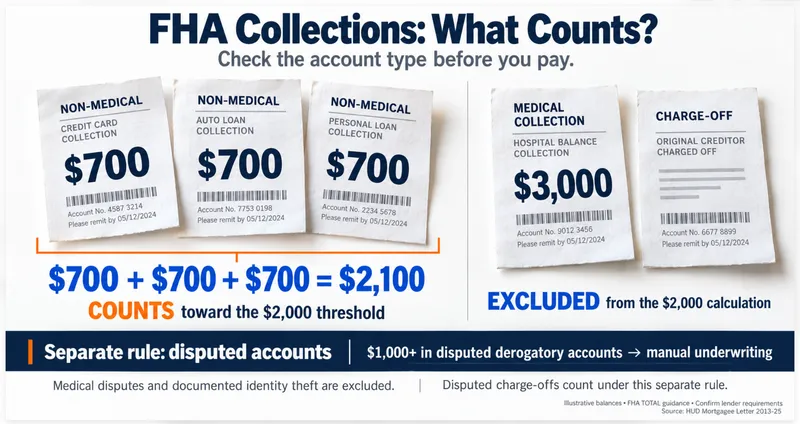
A larger collection is not always the one that needs attention first. Under FHA’s collection-account guidance, a $3,000 medical collection falls outside the $2,000 threshold, while three non-medical collections of $700 each cross it. The account type and combined balance matter more than the size of any single bill.
Disputes introduce a separate calculation. Disputed derogatory accounts totaling $1,000 or more generally require manual underwriting, with exclusions for medical disputes and documented identity theft. Charge-offs excluded from the $2,000 collection calculation still count under the disputed-account rule when contested.
That leaves buyers with more to consider than which collector to pay first. Paying an account reduces available cash; disputing an inaccurate entry requires evidence and coordination with your lender.
At ASAP Credit Repair USA, our collection reviews examine ownership, balances, dates and reporting status before identifying errors to challenge.
This guide explains which accounts count, what each threshold changes and which questions to settle with your lender before spending your closing funds.
FHA Loans and Collections: Which Accounts Need Attention Before You Apply?
FHA loan collection accounts raise one question for most buyers: do I have to pay them before I apply? HUD does not require payoff as a condition of approval, but three rules still decide how a collection affects your file.
The first rule is a $2,000 line. When your non-medical collection balances reach $2,000 combined, the lender must verify payment, document a payment arrangement, or count 5% of the balance as a monthly debt.
The second rule is a $1,000 line. Disputed derogatory accounts that total $1,000 or more push an automated approval into manual underwriting.
The third rule is an exclusion: medical collections and charge-offs sit outside the $2,000 calculation.
Most buyers never check which side of these lines they stand on. They pay a small old collection, drain their closing cash, and leave the real trigger untouched.
At ASAP Credit Repair USA, we review credit reports for inaccurate, incomplete, and unverifiable collection entries every day. We do not promise approval, because the lender and HUD's underwriting rules decide.
This guide shows how to sort your collections, total the ones that count, choose between payoff, an arrangement, and the 5% calculation, and handle disputes before the lender pulls your file.
FHA does not require you to pay off collection accounts to get approved. If your non-medical collections total $2,000 or more, the lender must verify payoff, document a payment arrangement, or add 5% of the balance to your monthly debts. Medical collections and charge-offs are excluded, and disputed derogatory accounts of $1,000 or more trigger manual underwriting.
Do FHA Loans Require You to Pay Off Collection Accounts?
No. HUD states that FHA does not require collection accounts to be paid off as a condition of mortgage approval. Collections still matter, because balances at or above $2,000 change how the lender calculates your debt-to-income ratio.
These rules come from HUD Mortgagee Letter 2013-25 and FHA Handbook 4000.1, Part II.A.4.b, which govern loans that run through FHA's TOTAL Scorecard. Each lender decides whether to add stricter rules of its own, so confirm its policy before you act.
| Account Type | How FHA Treats It |
|---|---|
| Non-medical collections under $2,000 combined | The lender is not required to evaluate them when the loan receives an Accept rating |
| Non-medical collections of $2,000 or more combined | Lender verifies payoff, documents a payment arrangement, or counts 5% of the balance as a monthly payment |
| Medical collections | Excluded from the $2,000 guidance |
| Charge-off accounts | Not included in your liabilities or debt |
| Disputed derogatory accounts of $1,000 or more | Loan downgrades to manual underwriting |
| Disputed accounts from documented identity theft | Excluded from the $1,000 limit with supporting documents |
Not Sure Which Collections Count?
Start with your credit reports. A review shows which collections are accurate, which are wrong, and how they total against the FHA lines.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhich Collection Accounts Count Toward the $2,000 Threshold?
All open non-medical collection accounts on your credit reports count, added together. Medical collections and charge-offs do not count. Add the balances of every other collection to see whether you reach $2,000.
The threshold uses the cumulative outstanding balance, not the largest account. Four $600 collections reach the line even though no single account looks serious.
In a community property state, a non-borrowing spouse's collections count toward the $2,000 unless state law excludes them. Ask your lender how it applies that rule in your state.
A Worked Example
Here is a hypothetical borrower with three non-medical collections. The borrower earns $5,000 per month before taxes.
| Collection | Balance | Counts Toward $2,000? |
|---|---|---|
| Utility account | $450 | Yes |
| Cable account | $900 | Yes |
| Credit card collection | $1,100 | Yes |
| Cumulative balance | $2,450 | Over the line |
| 5% of $2,450 | $122.50 per month | Adds 2.45 points to DTI |
How Do Lenders Treat Collections of $2,000 or More?
The lender picks one of three paths: verify the collections are paid in full by settlement, verify a payment arrangement with the creditor, or calculate a monthly payment at 5% of each balance. You choose among the options your lender offers.
| Option | What Happens | Cost to You | Documentation |
|---|---|---|---|
| Pay in full | Collections are paid at or before settlement | The full balance in cash, from acceptable funds | Payoff statement or proof of payment |
| Payment arrangement | The agreed monthly payment enters your DTI | Monthly payments | The written arrangement with the creditor |
| 5% calculation | 5% of each balance counts as a monthly debt | No payment, but a higher DTI | None required |
In the worked example, an arrangement of $100 per month beats the 5% figure of $122.50 on DTI. Paying the $2,450 outright removes the monthly debt entirely but uses cash you need for the down payment and closing costs.
Run all three scenarios with your lender before choosing. The best option depends on your DTI, your cash reserves, and how close you sit to the lender's limit.
What Happens If You Dispute a Collection During an FHA Application?
Disputed derogatory accounts, meaning disputed collections, disputed charge-offs, and disputed accounts with late payments in the last 24 months, total toward a $1,000 limit. At $1,000 or more, an automated approval downgrades to manual underwriting.
Manual underwriting means a person applies stricter guidelines to the whole file. That outcome costs you time and options, so finish disputes before you apply.
HUD excludes two kinds of disputes from the $1,000 limit: disputed medical accounts, and accounts disputed because of identity theft, card theft, or unauthorized use. The identity theft exclusion requires supporting documentation, such as a credit report, a creditor letter, or a police report.
A credit reporting agency has 30 days to reinvestigate a dispute, or 45 days if you send relevant new information in that window, under FCRA Section 611. Start at least 45 days before you apply, so the result is on your reports when the lender pulls them.
How to Review Your Collections Before You Apply for an FHA Loan
- Pull all three reports. Free reports are available at AnnualCreditReport.com. Collections differ by bureau.
- List every collection. Record the collector, original creditor, balance, date opened, and status for each one.
- Sort the list. Mark each account as medical, non-medical, charged-off, or disputed.
- Check accuracy. Compare each entry with your own records: ownership, balance, dates, and status. Mark anything wrong.
- Dispute the errors. Send each dispute to the bureau and the furnisher with evidence attached, and finish this step before you apply.
- Total the non-medical collections. Compare the sum with $2,000, and compare disputed derogatory balances with $1,000.
- Ask the lender how it applies the rules. Ask about payoff, arrangements, the 5% calculation, and any stricter lender rules.
- Decide, then document. Keep payoff statements, arrangement letters, and dispute results in one folder.
What to Do With Each Type of Account
| What You Find | Your Next Step |
|---|---|
| A collection that is not yours or has wrong details | Dispute with evidence and finish before applying |
| An accurate collection and your total is under $2,000 | Leave it. FHA does not require payoff at this level |
| An accurate collection and your total is $2,000 or more | Compare payoff, an arrangement, and the 5% calculation with your lender |
| A medical collection | Keep it out of your $2,000 total, and review it separately |
| A charge-off | No FHA payment calculation applies. Check the report for accuracy |
| Several open disputes | Total the derogatory ones against $1,000 and resolve them first |
Should You Pay a Collection Before Applying for an FHA Loan?
Pay only when it solves a specific FHA problem, such as keeping your total below the $2,000 line or lowering your DTI. Payment does not delete the entry from your report, and FHA does not require it. Ask the lender before you send money.
Paying a collection leaves the entry on your reports, and the score effect is uncertain. Our article on whether paying collections improves your score explains why.
Cash matters just as much. A payoff comes out of the same funds that cover your down payment, closing costs, and reserves.
Get any payment arrangement or payoff agreement in writing before you pay. The lender needs that document, and a verbal promise does not satisfy the underwriter.
What About Medical Collections on an FHA Loan?
HUD excludes medical collections from the $2,000 guidance and from the $1,000 disputed-account limit. They still appear on your reports, and they still affect your score.
Our supporting guides cover them in full. Read what to do if medical bills go to collections and how long medical debt stays on your credit report.
For the broader FHA rules on credit score and down payment, see our guide to credit scores and mortgage approval. FHA allows 3.5% down at a 580 score and 10% down for scores of 500 to 579, according to NerdWallet's FHA guide.
A Hypothetical Collection Review, Step by Step
Consider a hypothetical buyer with four accounts: a $1,800 medical collection, a $3,000 charged-off credit card, a $600 utility collection, and a $750 collection that belongs to someone else.
| Account | Balance | Treatment |
|---|---|---|
| Medical collection | $1,800 | Excluded from the $2,000 total |
| Charged-off credit card | $3,000 | Excluded from debt calculations |
| Utility collection | $600 | Counts |
| Collection that belongs to someone else | $750 | Dispute it; counts until removed |
| Cumulative non-medical collections | $1,350 | Under the $2,000 line |
The $6,150 in face value shrinks to $1,350 that counts, and the dispute removes $750 of that. The buyer pays nothing and files one dispute.
Add one more $900 collection and the total reaches $2,250. That single account crosses the line and forces a payoff, an arrangement, or the 5% calculation of $112.50 per month.
When Does Professional Credit Repair Make Sense Before an FHA Application?
Some buyers dispute the same collection repeatedly and get a verified result each time. They never learn why the entry stays, and the open dispute status keeps counting against the $1,000 line.
A review checks account ownership, balances, dates, payment history, and prior dispute results. ASAP Credit Repair USA helps consumers identify and address credit-report inaccuracies, and credit repair does not replace repaying an accurate debt or guarantee an FHA approval.
Not Sure What's Hurting Your Credit?
Start by reviewing your credit reports. ASAP Credit Repair USA helps consumers identify inaccurate account information and understand the appropriate steps for addressing reporting errors.
Review My Credit Report → Secure · 2 minutes · No credit card requiredFrequently Asked Questions About FHA Loan Collection Accounts
Do FHA loans require collections to be paid off?
No. HUD states that FHA does not require collection accounts to be paid off as a condition of mortgage approval. When non-medical collections total $2,000 or more, the lender must verify payoff, document a payment arrangement, or count 5% of the balance toward your monthly debts.
How much in collections is allowed on an FHA loan?
No hard cap exists. Under $2,000 in combined non-medical collections, the lender is not required to evaluate them when the loan receives an Accept rating. At $2,000 or more, one of three treatments applies. Each lender sets its own additional limits, so ask yours.
Do medical collections count against an FHA loan?
HUD excludes medical collections from the $2,000 guidance, and disputed medical accounts are excluded from the $1,000 disputed-account limit. They still appear on your credit reports and affect your score, so review each one for accuracy like any other entry.
Does FHA count charged-off accounts?
FHA Handbook 4000.1 states that charge-off accounts do not need to be included in your liabilities or debt. Charge-offs stay out of the collection calculation, though they still hurt your score and show on your reports. A disputed charge-off counts toward the $1,000 disputed-account limit.
What is the 5% rule for FHA collections?
When collections reach $2,000 and you have no payment arrangement or payoff, the lender counts 5% of each outstanding balance as a monthly payment in your debt-to-income ratio. A $4,000 balance adds $200 per month. The payment is a calculation, not a bill you owe.
Do disputed collections affect an FHA loan?
Yes. Disputed derogatory accounts that total $1,000 or more downgrade an automated approval to manual underwriting. Disputed medical accounts and documented identity theft disputes are excluded. Resolve your disputes before you apply so the lender sees a settled report, not an open dispute.
Should I pay collections before applying for an FHA loan?
Pay only when it solves a specific problem, such as dropping below the $2,000 line or lowering your debt-to-income ratio. FHA does not require payment, and payment does not delete the entry. Ask your lender first, because a payoff uses cash you need for closing.
Will paying a collection raise my credit score?
Do not count on it. Payment changes the account's status, but it does not delete the entry from your report, and the score effect varies by scoring model. Dispute inaccurate collections instead, since a verified deletion removes the entry itself under the Fair Credit Reporting Act.
Is an FHA loan possible with collections and a 580 score?
Yes. FHA allows 3.5% down at a 580 score and 10% down for scores of 500 to 579, according to NerdWallet. Collections do not bar approval by themselves, though many lenders set higher score minimums than FHA does. Confirm the lender's minimum before you apply.
Does the lender need an explanation letter for collections?
FHA Handbook 4000.1 states that the lender is not required to obtain an explanation of collection accounts or charge-off accounts. A lender still requests a letter when it wants one. Ask what yours expects, and keep the written explanation short and factual.
What if a collection on my report belongs to someone else?
Dispute it with the bureau and the furnisher, and include identity documents. HUD excludes accounts disputed because of identity theft, card theft, or unauthorized use from the $1,000 limit when you supply support, such as a creditor letter or a police report.
Does credit repair guarantee FHA approval?
No. Credit repair corrects inaccurate reporting and guarantees no lender decision or score increase. The Credit Repair Organizations Act bars a provider from charging before the service is fully performed. The lender decides on score, debt-to-income ratio, income, and collections together.
Sort your collections before you pay any of them. Total the ones that count, resolve the disputes that trigger manual underwriting, and choose the cheapest path past the $2,000 line.
-
What to Do If Medical Bills Go to Collections How medical debt reaches a collector and the steps to verify and resolve it.
-
How Long Does Medical Debt Stay On Credit Report Reporting periods and the $500 threshold for medical debt.
-
What Credit Score Do I Need for a Mortgage? Score requirements by loan type, including FHA.
-
Does Paying Collections Improve Credit Score? What payment changes on your report and what it leaves in place.
- U.S. Department of Housing and Urban Development — Mortgagee Letter 2013-25, collection accounts and disputed derogatory credit
- U.S. Department of Housing and Urban Development — FHA Single Family Housing Policy Handbook 4000.1, Part II.A.4.b
- NerdWallet — FHA credit score and down payment requirements
- Federal Trade Commission — Credit Repair: How to Help Yourself
- 15 U.S.C. § 1681i — Fair Credit Reporting Act, procedure in case of disputed accuracy
- 15 U.S.C. § 1679b — Credit Repair Organizations Act, prohibited practices
- AnnualCreditReport.com — Free credit reports