A 580 credit score does not automatically stop you from financing a car in Chicago. The bigger question is what that loan could cost you.
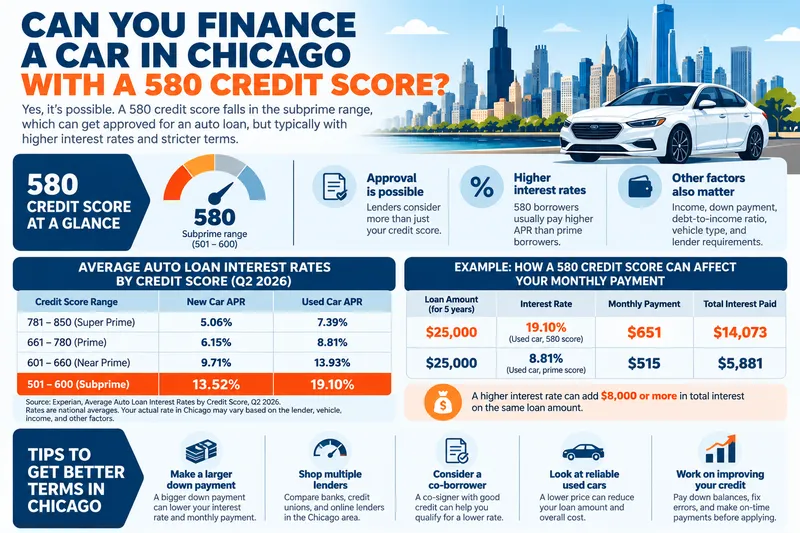
Experian's Q2 2026 auto-finance data places a 580 VantageScore in the 501–600 subprime range. Borrowers in that range received average rates of 13.52% on new-car loans and 19.10% on used-car loans. Prime borrowers, by comparison, averaged 6.15% and 8.81%.
That difference matters when you are financing thousands of dollars for several years.
“At 580, I would look beyond whether a lender says yes,”. I know this as the owner of ASAP Credit Repair USA. “The APR, amount financed, down payment, loan term, and what is actually pulling the credit score down can matter more than the approval itself.”
Can You Get a Car Loan With a 580 Credit Score in Chicago?
Yes, you can finance a car in Chicago with a 580 credit score. The real question is what it costs. This guide breaks down the actual rates Chicago lenders quote at that score, the legal limit Illinois places on auto loan interest, and what a 580 score really adds up to over the life of a loan.
Can You Actually Finance a Car in Chicago With a 580 Credit Score?
Yes. A 580 credit score falls into the subprime tier, and most Chicago dealerships, credit unions, and online lenders will still approve financing at that score. Approval is common, but the loan will carry a significantly higher interest rate and may require a larger down payment than a borrower with good or excellent credit.
A 580 score is not a barrier to approval in Chicago. It is a barrier to a good rate. Subprime lending exists specifically to serve this credit range, and Chicago has no shortage of dealers built around it, from major franchise stores with in-house subprime desks to buy-here-pay-here lots that finance in-house and report minimally, if at all, to the credit bureaus.
What Interest Rate Can You Expect With a 580 Credit Score in Chicago?
Nationally, a 580 credit score averages around 13.52 percent APR on a new car and 19.10 percent on a used car, according to Experian's latest credit tier data. Chicago-area subprime and buy-here-pay-here dealers often quote 18 to 29 percent APR, reflecting both the local market and the added risk premium those dealers price in.
| Credit Score | Avg. New Car APR | Avg. Used Car APR |
|---|---|---|
| 781+ (Excellent) | 4.41% | 6.9% |
| 661-780 (Good) | 6.5% approx. | 9.3% |
| 601-660 (Fair) | 9.8% approx. | 13.9% |
| 501-600 (Subprime, includes 580) | 13.52% | 19.1% |
| 300-500 (Deep Subprime) | 16.11% | 21.6% |
Is There a Legal Limit on Auto Loan Interest Rates in Illinois?
Yes. Illinois's Predatory Loan Prevention Act caps the annual percentage rate on consumer credit, including loans made under the Motor Vehicle Retail Installment Sales Act, at 36 percent. Any Chicago dealer or lender quoting an APR above that ceiling on a standard auto purchase loan is exceeding the legal limit.
This is a genuine consumer protection worth knowing before you sign anything in Chicago. Illinois passed the Predatory Loan Prevention Act in 2021, setting a hard 36 percent APR ceiling across several consumer credit laws, including the one that governs standard vehicle purchase financing. Before the cap, Illinois consumers took out roughly 1.04 million high-cost loans a year; after it took effect, that number fell to just over 100, according to research from the Woodstock Institute.
How Much Does a 580 Credit Score Actually Cost on a Car Loan?
On a $25,000 loan over 60 months, a 580 credit score typically costs about $5,600 more in total interest than an excellent credit score near 720 or above, based on national rate averages. Stretching the loan to 72 months to lower the monthly payment increases that interest gap even further.
Roughly $472 a month, with approximately $3,300 to $3,800 in total interest over the life of the loan.
Roughly $566 a month, with total interest climbing into the $9,000 to $13,000 range depending on the exact rate and term.
The gap gets worse, not better, on a longer loan. Stretching to 72 months lowers the monthly payment but adds another year of interest at the higher subprime rate, which is part of why approval odds and true costs at a 580 score are worth understanding before choosing a loan term, not just a monthly payment.
See What Raising Your Score Could Save You in Chicago
A free 3-bureau review shows exactly what is holding your score at 580, so you know whether a dispute or two could move you into a better rate tier before you finance.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Credit Score Does the Dealer Actually See?
Chicago dealers typically pull a FICO Auto Score, a specialized version of your credit score built specifically to predict auto loan repayment risk, rather than the general-purpose score shown on a free credit app. It runs on a wider 250 to 900 scale and can land higher or lower than the score you check yourself.
This catches a lot of Chicago car buyers off guard. The 580 you see on a free credit app is useful context, but it is not necessarily the exact score a dealer's finance department will pull, since auto-specific scoring models weight past auto loan history more heavily than a general credit score does.
How to Get a Better Deal Before You Finance
- ✓ Get pre-approved through a credit union or online lender before visiting a Chicago dealership
- ✓ Pull your credit report and dispute any inaccurate or outdated accounts first
- ✓ Save for a 15-20% down payment to reduce the loan amount and improve approval odds
- ✓ Compare at least two or three financing offers instead of accepting the first dealer quote
- ✓ Confirm any quoted APR is at or below Illinois's 36% legal ceiling
- ✓ Choose the shortest loan term you can afford, since a longer term at a subprime rate compounds the total interest cost
A 580 score will get you approved almost anywhere in Chicago. The real decision is whether you finance today at a subprime rate or spend a few weeks improving what is fixable on your credit report first, since even a modest score increase can shift you into a meaningfully cheaper rate tier.
Financing a car in Chicago with a 580 credit score is realistic and common. The cost is the part to plan for, with national subprime rates averaging 13.52% to 19.1% APR and local dealers often quoting toward the higher end of that range. Illinois's 36% rate cap sets a legal ceiling, but shopping multiple lenders and improving what is fixable on a credit report first both do more to lower the actual cost than the cap alone.
Can I finance a car in Chicago with a 580 credit score?
Yes. A 580 credit score falls into the subprime tier, and most Chicago dealerships, credit unions, and online lenders will still approve financing at that score. Approval is common, but the loan will carry a significantly higher interest rate and may require a larger down payment than a borrower with good or excellent credit.
What interest rate can I expect with a 580 credit score in Chicago?
Nationally, a 580 credit score averages around 13.52 percent APR on a new car and 19.10 percent on a used car, according to Experian's latest credit tier data. Chicago-area subprime and buy-here-pay-here dealers often quote 18 to 29 percent APR, reflecting both the local market and the added risk premium those dealers price in.
Is there a legal limit on auto loan interest rates in Illinois?
Yes. Illinois's Predatory Loan Prevention Act caps the annual percentage rate on consumer credit, including loans made under the Motor Vehicle Retail Installment Sales Act, at 36 percent. Any Chicago dealer or lender quoting an APR above that ceiling on a standard auto purchase loan is exceeding the legal limit.
How much does a 580 credit score cost you on a car loan?
On a $25,000 loan over 60 months, a 580 credit score typically costs about $5,600 more in total interest than an excellent credit score near 720 or above, based on national rate averages. Stretching the loan to 72 months to lower the monthly payment increases that interest gap even further.
What can I do to get a better rate before financing a car in Chicago?
Get pre-approved through a credit union or online lender before visiting a dealership, put down 15 to 20 percent if possible, and check your credit report for disputable errors first, since even a 40-point score increase can meaningfully lower the quoted APR. Comparing at least two or three offers also helps avoid the highest end of the subprime rate range.
Don't Finance at 580 Without Checking What's Fixable First
A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion currently report, so you can walk into a Chicago dealership knowing your real number, not just an app's estimate.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
Bad Credit Car Dealerships in Chicago: How to Get Approved Covers how Chicago subprime dealers structure financing and what a 40-point score increase can save on interest.
-
Can You Buy a Car With a 580 Credit Score? Approval Odds A full breakdown of approval odds, expected rates, and monthly payment differences at a 580 score.
-
What Credit Score Auto Loan Dealers Really Use Explains the FICO Auto Score model dealers pull and why it can differ from the score on a free credit app.
-
Bad Credit Car Loans: Complete Guide to Getting Approved A step-by-step guide to pre-approval, lender comparison, and negotiating a subprime auto loan.
-
Experian: Average Car Loan Interest Rates by Credit Score The national data source for average new and used car APRs across every FICO credit tier.
-
Woodstock Institute: Illinois's Rate Cap Has Saved Consumers Over $600 Million Research on the impact of Illinois's 36% Predatory Loan Prevention Act rate cap since it took effect.
-
Illinois Auto Loan Rates 2026: Average APR and Credit Score Needed Current Illinois-specific auto loan rate data and how the state compares nationally.
Remember: 580 does not automatically prevent auto-loan approval. There is no universal minimum score because individual lenders set their own underwriting requirements. The CFPB's current auto-loan dataset even tracks originations specifically for borrowers with FICO scores of 580–619, confirming that this segment continues to receive new auto loans.