Low credit score car loans do not follow one universal rulebook. There is no single minimum credit score across auto lenders; approval depends on the lender's underwriting, income, existing debt, credit history, the vehicle itself, and the down payment. A borrower with a 540 score gets approved at one lender and denied at another, same day, same paperwork.
The real risk is not approval, it is cost. Subprime borrowers made up 15.75% of total vehicle financing in Q1 2026, up from 14.40% a year earlier, per Experian's State of the Automotive Finance Market report.
A higher APR on the same loan amount adds thousands in interest over a typical five-year term, and that gap is where a low-score borrower loses the most money.
This guide covers verified lender options for people with low credit scores. We'll discuss what score ranges mean for approval, real loan-cost math across APRs, and when fixing the credit report first beats financing today.
Low Credit Score Car Loans: Best Lenders, Rates, and Approval Tips
Low credit score car loans come from banks, credit unions, dealer-arranged lenders, online lenders, and specialized subprime programs. No single minimum score applies everywhere; approval depends on the lender, income, debt, credit history, the vehicle, and the down payment.
A lower score generally means a higher APR, which raises both the monthly payment and the total interest paid.
Best Low Credit Score Car Loans in 2026
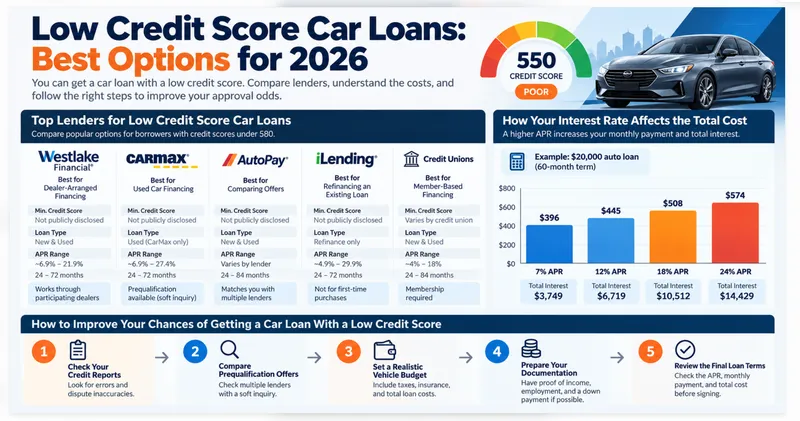
The strongest verified options for low credit score car loans are dealer-arranged financing through networks like Westlake Financial, CarMax's in-house financing for used vehicles, lender-matching services like Autopay for comparing offers, iLending for refinancing an existing loan, and credit unions for members who qualify.
| Provider | Best Use Case | Published Min. Score | Loan Type | Prequalification |
|---|---|---|---|---|
| Westlake Financial | Dealer-arranged bad credit financing | Not publicly disclosed | New and used purchase | Yes, online |
| CarMax | Used car purchase financing | Not publicly disclosed (lists a "below 580" tier) | Used purchase only | Yes, online |
| Autopay | Comparing multiple financing offers | Not publicly disclosed | Purchase and refinance (lender-matching network) | Yes, online |
| iLending | Refinancing an existing car loan | 560 | Refinancing only, not new purchases | Yes, online |
| Credit Unions | Member-based financing comparison | Varies by institution | Purchase and refinance | Varies by institution |
Best Low Credit Score Car Loans for Scores Below 580
For scores below 580, dealer-arranged lenders like Westlake Financial and in-house programs like CarMax's tend to approve more consistently than traditional banks, while Autopay compares several offers at once and iLending only helps once a loan already exists to refinance.
Westlake Financial: Best for Dealer-Arranged Bad Credit Financing
Westlake works through roughly 30,000 partner dealerships and offers online prequalification before a dealer visit, without affecting the credit score. No minimum score is published; the dealer partner reviews income, employment, and the vehicle.
Pros and cons: Wide dealer network and fast prequalification, but the final rate depends on which dealer partner handles the file, and APRs are not published in advance.
Editorial take: Treat it as one offer among several. Compare its terms against a credit union quote before signing.
CarMax: Best for Used Car Financing
CarMax finances used vehicles from its own inventory, with online prequalification in minutes; the company reports more than 97% of applicants get prequalified, plus a published tier for scores below 580. No minimum score is published.
Pros and cons: Simple, in-house process, but financing applies only to vehicles purchased from CarMax, not elsewhere.
Editorial take: A solid stop for used-car shoppers specifically; it will not finance a private-seller or another dealer's vehicle.
Autopay: Best for Comparing Available Auto Financing Offers
Autopay matches one application to a network of lending partners for both purchase financing and refinancing. No minimum score is published; the strongest rates go to well-qualified borrowers who also meet income and debt-to-income requirements.
Pros and cons: One application reaches several lenders, saving time, but final terms come from whichever partner approves the file, not Autopay itself.
Editorial take: Useful for comparison shopping before committing to one lender's offer.
iLending: Best for Refinancing an Existing Car Loan
Current car owners with an existing loan who want a lower rate after their credit has improved are the target customer. iLending publishes a minimum credit score of 560, more transparent than most competitors here, though meeting that threshold does not guarantee approval.
Editorial take: Worth revisiting months after the original purchase once the score has moved, not at the point of buying.
Credit Unions: Best for Comparing Member-Based Financing
A credit union is not one lender; it is a category of thousands of member-owned institutions, and underwriting varies by institution. Most require membership, often through an employer, location, or a small deposit, before quoting a rate.
Editorial take: Always worth a quote before accepting dealer financing, since terms vary enough that one credit union's no is not every credit union's answer.
Before You Finance a Car, Know What Your Credit Report Says
An inaccurate late payment or a duplicate collection pushes a borderline score into a worse pricing tier. A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion currently report before you apply anywhere.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Credit Score Do You Need for a Car Loan?
No single score guarantees or blocks car loan approval. FICO Scores below 580 are generally labeled subprime. A score of 580 is a common reference point, not a universal approval line; income, debt-to-income ratio, and the vehicle itself also factor into the decision.
| Score Range | Editorial Comparison Band |
|---|---|
| 300-500 | Deep subprime; fewest lenders, highest published APRs, larger down payment often expected |
| 501-579 | Subprime; dealer-arranged and specialized lenders are the most consistent approvals |
| 580-600 | Near-prime entry; more lenders become available, rates still well above prime |
| 601-619 | Near-prime; credit unions and banks start competing seriously for the loan |
| 620-660 | Prime entry; published bank and credit union rates typically improve noticeably |
| 661 and above | Prime; access to the widest lender pool and the lowest published rate tiers |
How Much Do Low Credit Score Car Loans Cost?
On a $20,000 loan over 60 months, raising the APR from 7% to 24% increases the monthly payment from about $396 to about $575 and adds roughly $10,760 in total interest over the life of the loan. The payment difference looks small month to month; the total-cost difference is not.
| APR | Monthly Payment | Total Interest | Total Repayment | Difference vs. 7% |
|---|---|---|---|---|
| 7% | $396 | $3,761 | $23,761 | — |
| 12% | $445 | $6,693 | $26,693 | +$2,932 |
| 18% | $508 | $10,472 | $30,472 | +$6,711 |
| 24% | $575 | $14,522 | $34,522 | +$10,760 |
A longer term lowers the monthly payment but usually raises total interest, since the balance stays higher for longer at the same rate. Stretching a loan from 60 to 72 or 84 months to shrink the payment often costs more overall, even when the APR stays fixed.
How to Get a Car Loan With a Low Credit Score
1. Check All Three Credit Reports Before Applying
Pull reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com and look for inaccurate late payments, duplicate collections, wrong balances, and accounts that do not belong to you. Any of these, if genuinely wrong, pushes a borrower into a worse pricing tier than the real history supports.
2. Compare Prequalification Offers Before Submitting Applications
Prequalification typically uses a soft inquiry, which does not affect the score; a full application triggers a hard inquiry. FICO scoring models generally treat multiple auto-loan inquiries made within a short window, 14 to 45 days depending on the model version, as a single inquiry for scoring purposes.
3. Set a Maximum Vehicle Budget Based on Total Cost
Total cost includes the loan payment plus taxes, registration, insurance, maintenance, and likely repairs, not just the sticker price divided by 60 months.
4. Prepare Proof of Income and Employment
Pay stubs, bank statements, or tax documents matter because repayment capacity, not just the credit score, drives the lender's decision.
5. Compare Down Payment Requirements
A larger down payment reduces the financed balance and loan-to-value ratio, which some lenders weigh heavily on subprime applications. It changes the numbers the lender is underwriting, though it does not guarantee a better rate.
6. Review the Final APR and Loan Contract
APR, interest rate, amount financed, monthly payment, and total repayment are five different figures on the same contract. Confirm each one before signing, since a dealer can adjust the term or add products that change the total cost without changing the advertised rate.
Low Credit Score Car Loans With No Down Payment
Zero-down financing exists, but it increases the amount financed and the risk of owing more than the vehicle is worth. Advertised zero-down offers are not the same as guaranteed approval; the lender still underwrites income, debt, and the vehicle before approving any amount.
Skipping the down payment means financing the full purchase price plus taxes and fees from day one, raising both the monthly payment and total interest versus the same loan with money down. It also widens the window of negative equity, owing more than the car is worth, since a new vehicle loses value faster than a zero-down loan pays down principal early on. Some lenders apply stricter requirements to zero-down applications. Compare the full cost against a small down payment first; see why an accurate credit report still leads to denial for related approval factors.
Should You Get a Car Loan Now or Improve Your Credit First?
The decision depends on how urgently transportation is needed, whether the credit report contains fixable errors, the APR offers already on the table, available down payment, and existing monthly debt. Neither path guarantees a specific outcome.
Hypothetical: a borrower starts a new job next week with no other transportation option. Waiting is not realistic, so the focus shifts to comparing available offers on affordability and total cost.
Hypothetical: a borrower's current car still runs and the credit report shows a documented, disputable error. Correcting that error first, before applying, is the stronger move here.
A credit improvement never guarantees movement into a specific lender pricing tier; lenders weigh the full application, not one number in isolation.
How Credit Repair Fits Into Low Credit Score Car Loans
Legitimate credit repair corrects inaccurate reporting; it does not guarantee loan approval or a specific rate. Disputing wrong late payments, duplicate accounts, or misattributed entries, and reducing revolving utilization before applying, addresses the parts of a credit file that are actually fixable.
Before financing a vehicle, it helps to separate what is wrong on a credit report from what is simply unfavorable. A late payment that genuinely happened, or a collection that is genuinely owed, generally remains reportable for the applicable legal period regardless of how it affects a car loan application. An inaccurate entry, a duplicate account, or a payment misreported as late is a different category, and that is the category a formal dispute addresses.
Specific steps that connect directly to auto financing: disputing inaccurate reporting, reviewing late-payment histories for errors, correcting duplicate or misattributed accounts, reducing revolving utilization, bringing past-due accounts current, and avoiding new debt in the months before applying.
ASAP Credit Repair USA does not provide auto loans and does not guarantee a specific score increase or lender approval. What it helps with is identifying the specific credit-report problems worth fixing before financing gets more expensive than it needs to be.
Mistakes to Avoid When Applying for Low Credit Score Car Loans
- ✗ Shopping by monthly payment alone. A lower payment stretched over a longer term often costs more in total interest.
- ✗ Accepting an unnecessarily long loan term. Seventy-two or eighty-four months lowers the payment but extends the period of owing more than the car is worth.
- ✗ Confusing prequalification with final approval. A prequalified offer is conditional, not a guaranteed rate or amount.
- ✗ Ignoring dealer add-ons and financing markups. Extended warranties and service contracts get added to the financed balance unless specifically declined.
- ✗ Overlooking negative equity from a trade-in. Rolling an underwater trade-in into a new loan increases the amount financed on the new vehicle.
- ✗ Signing before financing is final. A deal presented as approved sometimes still requires final lender sign-off after delivery.
- ✗ Choosing a buy-here-pay-here dealership without reviewing its reporting practices. Some buy-here-pay-here lenders do not report payments to any credit bureau at all, which means on-time payments build no credit history.
What are the best low credit score car loans in 2026?
Dealer-arranged lenders like Westlake Financial, CarMax's in-house financing for used vehicles, lender-matching services like Autopay, and credit unions a borrower qualifies to join. iLending only applies once a loan already exists to refinance.
Is a 500 credit score enough to get a car loan?
Often, yes, through dealer-arranged or specialized subprime lenders, though approval still depends on income, debt, and the vehicle. A 500 score sits in the deep subprime range, where published APRs run highest.
What is the lowest credit score accepted for car financing?
There is no single published floor. Some dealer-arranged and specialized lenders work with scores in the 500s or below; the vehicle, income, and down payment often matter as much as the score itself.
Which lenders work with credit scores below 580?
Dealer-arranged networks like Westlake Financial and in-house programs like CarMax's publish a credit tier specifically for scores challenged below 580. Neither publishes an exact minimum score.
What interest rate should I expect with a 550 credit score?
Rates in the deep subprime range run well above prime-tier offers, but exact APRs vary by lender, vehicle, term, and down payment. Compare at least two or three actual offers rather than relying on a single average figure.
Is a credit union better than a dealership for bad credit?
It depends on the institution. Credit unions often publish clearer rate sheets, but underwriting varies enough that comparing an actual quote against the dealer's offer is the only reliable test.
Does getting prequalified hurt my credit score?
Prequalification typically relies on a soft inquiry, which does not affect the score. A full loan application generates a hard inquiry, and FICO models generally group multiple auto-loan hard inquiries within a short window as one for scoring purposes.
How much down payment is needed with bad credit?
No fixed amount applies everywhere. A larger down payment lowers the financed balance and the loan-to-value ratio, which some subprime lenders weigh heavily, though it does not guarantee approval or a specific rate.
Is a co-signer necessary for a low credit score car loan?
Not always. A qualified co-signer sometimes improves approval odds or pricing, but requirements vary by lender and depend on the primary applicant's income and credit profile.
Should I repair my credit before buying a car?
If transportation is not urgent and the credit report contains a documented, fixable error, correcting it first sometimes improves the offers received. If transportation is needed immediately, comparing available offers on total cost is the more realistic path.
Are buy-here-pay-here loans reported to credit bureaus?
Not always. Some buy-here-pay-here dealerships do not report payment history to any credit bureau, which means consistent on-time payments build no credit history. Confirm reporting practices before signing.
Does refinancing help after a credit score improves?
It sometimes does. A refinancing lender like iLending reviews the improved score, the current loan balance, and the vehicle's value; a lower rate is not guaranteed, but it is worth checking once the score has moved meaningfully.
Final Takeaway: The Rate Matters More Than the Approval
Low credit score car loans are available through more channels than a single lender roundup suggests. The approval is rarely the hard part; the APR attached to it decides whether the vehicle costs thousands more than it needed to. Check the credit report for fixable errors first, compare actual offers side by side, and run the total-cost math before signing anything.
Ready to Shop for a Car Loan?
A reporting error you never noticed could be the difference between a subprime rate and a near-prime rate. A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion currently report before you apply.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
What Credit Score Is Needed to Buy a Car in 2026? A closer look at score requirements and how lenders weigh them against income and debt.
-
Credit Report Correct but Denied? 7 Reasons Why Why an accurate credit report still results in a loan denial, and what to check next.
-
How to File a TransUnion Dispute & Fix Credit Report Errors The full process for correcting an inaccurate entry before it affects a car loan application.
- Consumer Financial Protection Bureau — Auto loans and comparing offers
- Experian — State of the Automotive Finance Market, Q1 2026
- Federal Trade Commission — Buying a car or truck, financing and add-ons
- myFICO — Rate-shopping and auto-loan inquiry windows
- AnnualCreditReport.com — Free weekly credit reports