A poor credit score in Atlanta can affect far more than whether a lender approves a new credit card. It can influence the interest rate and terms offered on a mortgage, auto loan, or personal loan, making the cost of borrowing substantially higher over time. That matters locally because Atlanta consumers carried an average credit card balance of $7,825 in 2026, while the metro area's average FICO Score was 696, according to Experian.
Atlanta also trails the national credit benchmark.
Experian reported the average U.S. FICO Score at 713 in 2025, while only 19.8% of Atlanta-area consumers had a FICO Score of 800 or higher as of June 2026. These figures do not mean every Atlanta borrower faces the same lending outcome. Credit decisions can also depend on income, debt, payment history, loan type, and the scoring model a lender uses.
If your score is below the range required for the credit product you want, the first step is identifying what is pulling it down. Late payments, high credit utilization, collections, charge-offs, and inaccurate credit-report information can all matter.
This guide explains how poor credit works, what Atlanta consumers should check, and which actions may help improve credit over time.
What Does a Poor Credit Score Mean in Atlanta?
A poor credit score can make borrowing more expensive and limit the financial options available to Atlanta consumers. Lenders may view a lower score as a higher credit risk, which can result in higher interest rates, smaller credit limits, larger required deposits, or difficulty qualifying for certain loans.
The impact also depends on what is causing the score to fall. Late payments, high credit card utilization, collections, charge-offs, and inaccurate information on a credit report can all contribute. Identifying these factors is the first step toward deciding what needs attention.
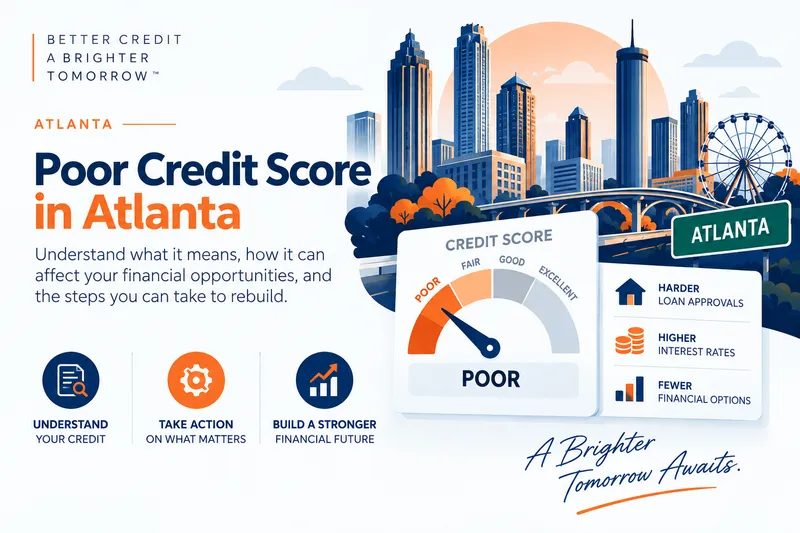
The graphic below shows how poor credit can affect common financial opportunities and why reviewing your credit profile before applying for new financing matters.
A poor credit score in Atlanta is not the story you would expect from a city with a median household income above the national average. Atlanta's average credit score is 628, according to WalletHub's 2026 rankings, 50 points below both the national average and the Georgia state average. The real cause is not a lack of money citywide. It is how unevenly that money is spread, combined with the nation's highest eviction filing rate and a Fulton County subprime rate near 30%. This article breaks down the real numbers behind Atlanta's score, why the usual "low income" explanation does not fully hold up here, and what actually moves a score once you understand the local pressure points.
What Is the Average Credit Score in Atlanta, GA?
Atlanta's average credit score is 628, according to WalletHub's 2026 city rankings. That is 50 points below the national average of 702 and also 50 points below the Georgia state average of 678, meaning Atlanta pulls its own state's number down.
A 628 score sits just inside "fair" credit, close to the line most lenders draw for subprime pricing. It usually means higher APRs on auto loans, larger security deposits on apartments and utilities, and denials on the best-rewards credit cards. The gap between Atlanta and the rest of Georgia is the more striking part. Most cities track close to their state's average. Atlanta sits a full 50 points under it.
Want to Know Exactly What's on Your Atlanta Credit File?
A collections account, a reporting error, or high utilization could be costing you more points than you realize. A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion currently report before you make any financial decision.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhy Doesn't a High-Income City Have a Higher Credit Score?
Atlanta's median household income of roughly $83,000 is above the national average, but Atlanta also has one of the widest income gaps of any major U.S. city. A high citywide average can hide a large share of residents earning far less, which drags the credit score average down.
This is the part that surprises people outside the city. Atlanta is not a poor city by the numbers. It is one of the most economically unequal ones. Research from Kindred Futures found that the income gap between white and Black households in Atlanta has grown to more than $73,000 a year, one of the widest such gaps of any major U.S. city. A citywide average income of $83,000 does not reflect a shared reality when a large share of households are earning closer to $39,000.
| Metric | Atlanta | Context |
|---|---|---|
| Citywide median household income | ~$83,251 | About 10% above the Georgia state average |
| Income gap, white vs. Black households | ~$73,563/year | Grown from ~$56,291 over the past decade |
| Citywide poverty rate | ~17.7% | Well above the roughly 12% national rate |
| Average credit score | 628 | 50 points below the national average |
A credit score does not measure income directly. It measures payment history and utilization. But income inequality makes both of those harder to manage for a large share of Atlanta residents, even while the city's overall economy looks strong on paper.
What Else Is Driving Atlanta's Credit Scores Down?
Beyond income inequality, three factors stand out: a roughly 30% subprime rate in Fulton County, credit card utilization well above the national average, and the nation's highest eviction filing rate, which strains household budgets before a payment is ever missed.
| Local Factor | Atlanta / Georgia Data | Risk to Credit Score |
|---|---|---|
| Fulton County subprime share | ~30% of credit files below 660 | Severe |
| Eviction filing rate | Highest of any major U.S. city (2025) | Severe |
| Cardholders using 75%+ of limit | About 1 in 3 Georgia cardholders | High |
| Average card debt vs. national | $8,657 in Georgia vs. ~$6,600 nationally | High |
| Median debt in collections | $1,893 in Atlanta | Moderate |
Utilization is the fastest of these to fix, and the math is worth understanding. Atlanta's pattern closely resembles what we see in other high-cost metros, covered in more depth in why credit card balances run so high: high balances that barely move because interest charges eat most of the monthly payment.
How Does Atlanta's Eviction Rate Connect to Credit Scores?
Atlanta had the highest eviction filing rate of any major U.S. city in 2025. An eviction filing itself does not appear on a credit report, but the missed rent, security deposit hikes, and collections accounts that come with housing instability do, and they compound fast.
Atlanta Legal Aid alone handled 20,000 cases in a single recent year, about half of them housing-related. Average rent climbed 17% between 2022 and 2023 before leveling off, and that kind of jump forces a lot of households to choose between rent and a credit card payment in the same month.
Card payments and rent both get made on time most months, keeping utilization and payment history steady.
A missed or late card payment often shows up in the same month as a rent shortfall, and the two problems tend to arrive together.
Atlanta's low average score is not a simple story about a poor city. It is a story about a wide income gap, a high subprime share concentrated in Fulton County, heavy credit card utilization, and the nation's highest eviction filing rate, all pushing in the same direction at once.
How Can Atlanta Residents Raise a Poor Credit Score?
Pay down credit card balances below 30% of the limit, dispute inaccurate or unverifiable collections under the Fair Credit Reporting Act, avoid closing old accounts, and address any high-utilization card that is reporting a large balance every month first.
- ✓ Pull your full credit report and identify which accounts are closest to their limit first
- ✓ Pay down the highest-utilization card before the highest-balance one, since utilization moves the score faster
- ✓ Dispute any account that is inaccurate, outdated, or unverifiable under the Fair Credit Reporting Act
- ✓ Keep old accounts open, since closing them raises utilization and shortens average account age
- ✓ Build a small emergency buffer if a rent increase is likely, so it does not land on a credit card
- ✓ Work with a credit repair company if a subprime score is limiting housing or auto loan options and disputes are not resolving on their own
Atlanta's income gap and eviction rate are citywide problems no single person can fix. But a credit score is still decided account by account, and knowing exactly which balance or collection is doing the most damage is what turns a subprime file into a fair or good one.
What is the average credit score in Atlanta, GA?
The average credit score in Atlanta, GA is 628, according to WalletHub's 2026 city rankings, placing it 97th out of 182 U.S. cities studied. That is 50 points below the national average of 702 and 50 points below the Georgia state average of 678.
Why does Atlanta have a poor average credit score if median income is high?
Atlanta's median household income of roughly $83,000 is above the national average, but Atlanta also has one of the widest income gaps of any major U.S. city. A high citywide average can mask a large share of residents earning far less, which is what drags the average credit score down.
What is a subprime credit score and how common is it in Atlanta?
A subprime score is generally any score below 660, which limits access to the best interest rates. In Fulton County, home to Atlanta, roughly 30% of the credit population held a subprime score as of late 2024, according to Federal Reserve and Equifax data.
How does Atlanta's eviction rate connect to credit scores?
Atlanta had the highest eviction filing rate of any major U.S. city in 2025. An eviction filing itself does not appear on a credit report, but the missed rent payments, collections accounts, and credit checks that come with housing instability do, and they compound quickly.
How can Atlanta residents improve a poor credit score?
Pay down credit card balances below 30% of the limit, dispute inaccurate or unverifiable collections under the Fair Credit Reporting Act, avoid closing old accounts, and address any subprime auto loan or high-utilization card that is actively reporting a high balance every month.
Find Out What's Really Driving Your Atlanta Score
High utilization, an old collection, or a reporting error could all be costing you points right now. A free 3-bureau audit shows exactly what Equifax, Experian, and TransUnion report on your file today.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
Is 600 a Good Credit Score? Honest Breakdown, Costs & How to Improve Explains exactly what a subprime score costs in real dollars and what separates it from "fair" and "good" credit.
-
Credit Card Balances: Why They're So High Breaks down why high-interest balances barely shrink even with faithful monthly payments, and how to fix it.
-
What Is the Lowest Credit Score? Complete Guide Covers the real-world costs of a low score, from rental deposits to insurance premiums, and the realistic path back up.
-
Collection Bureau of America: Remove It & Repair Credit Fast A step-by-step guide to disputing or resolving a collections account before it does further damage.
-
WalletHub: Cities With the Highest & Lowest Credit Scores (2026) The city-by-city credit score data referenced throughout this article, including Atlanta's full ranking.
-
Bisnow: Why Atlanta Has Become the U.S. Capital of Eviction Filings Reporting on Atlanta's 2025 eviction filing data and the local housing pressures behind it.
-
Kindred Futures: Poverty, Income, and Black Wealth in Atlanta The income inequality research cited in this article's breakdown of Atlanta's income gap.