Buying a house in Columbus with a 600 credit score may be possible, but qualifying for a mortgage and getting favorable loan terms are two different questions. If your score is sitting at 600, you are likely trying to determine whether you should apply now, improve your credit first, or find a loan program designed for borrowers in your current credit range.
The numbers make that decision especially relevant in Columbus. The city's median home sale price was $299,802 in August 2026, with homes taking a median of 42 days to sell. Meanwhile, a 600 score is above the 580 baseline associated with FHA's 3.5% down option, but it remains below the thresholds stated in this guide for many conventional loans and Ohio Housing Finance Agency down payment assistance programs.
That gap reflects a common concern among lower-score homebuyers. That's being eligible for one mortgage path does not necessarily mean you qualify for every loan, assistance program, or competitive rate. Credit score is only part of underwriting. Lenders can also review income, debt-to-income ratio, payment history, down payment, and the rest of the credit file.
This guide explains whether you can buy a house in Columbus with a 600 credit score.
We'll talk about which mortgage options may be available, how Ohio down payment assistance differs from basic FHA eligibility, what a lower score can mean for borrowing costs, and what to review before applying.
Can You Buy a House in Columbus With a 600 Credit Score?
Yes, buying a house in Columbus with a 600 credit score is possible. A 600 score is above FHA's baseline 580 threshold for maximum financing, but a credit score alone does not determine mortgage approval. Lenders also review your income, debt-to-income ratio, employment, down payment, credit history, property, and other underwriting factors.
Conventional and Ohio down payment assistance programs may have different or higher requirements.
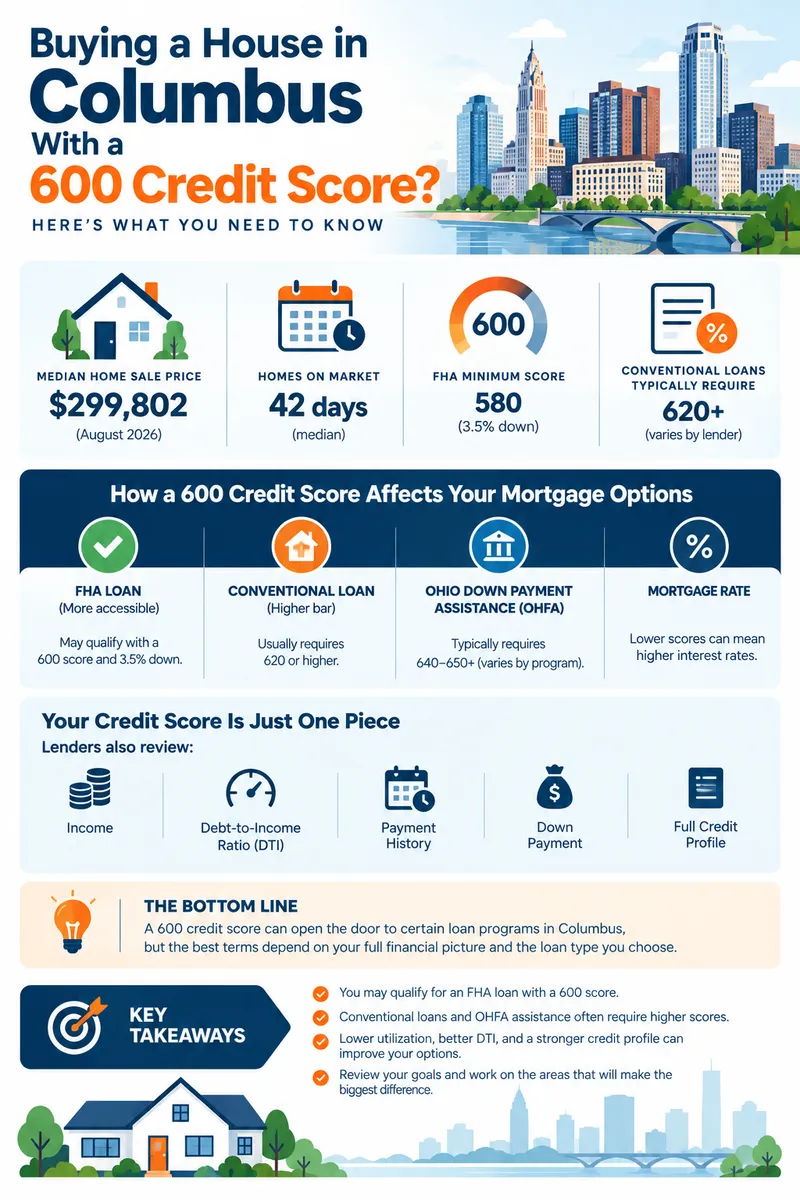
A 600 credit score is enough to buy a house in Columbus, but the path there runs through FHA financing, not a conventional loan. FHA's 580 minimum leaves a 600 score with real room to spare, while most conventional programs set their floor at 620 or higher. This guide lays out exactly what a 600-score buyer qualifies for in Columbus today, what it costs compared to a stronger score, and which local programs are and are not within reach yet.
Can You Buy a House in Columbus With a 600 Credit Score?
Yes. A 600 credit score clears the 580 minimum for an FHA loan with 3.5% down. It falls short of most conventional loan minimums, which typically start at 620, so FHA financing is the realistic path for a 600-score buyer in Columbus.
According to Experian's breakdown of FHA loan qualification, a score of 580 or above opens the door to a 3.5% down payment, while a score between 500 and 579 still qualifies with 10% down. A 600 score sits comfortably inside the low down payment tier, twenty points clear of the line that would push the required down payment much higher.
Conventional loans tell a different story. Most conventional programs start at a 620 minimum, and some lenders layer on stricter overlays for buyers closer to that floor. A 600-score buyer applying conventional is likely to face a denial or a steep rate penalty, which is why FHA remains the more realistic route until the score climbs further.
What Credit Score Do You Need to Buy a House in Ohio?
FHA loans require a minimum 580 score for 3.5% down, or 500 to 579 with 10% down. Conventional loans typically require 620 or higher. Ohio's state down payment assistance program, OHFA, sets its own higher floor of 650 for FHA loans and 640 for conventional, USDA, and VA loans.
| Loan Type | Minimum Score | Down Payment |
|---|---|---|
| FHA (500–579) | 500 | 10% |
| FHA (580+) | 580 | 3.5% |
| Conventional | 620 | 3–20%, varies |
| OHFA down payment assistance, government loans | 650 | 3.5% assistance grant |
| OHFA down payment assistance, conventional/USDA/VA | 640 | 3% assistance grant |
This is the detail that surprises a lot of Columbus buyers. Ohio's own assistance program is not aligned with FHA's baseline. A 600-score buyer already qualifies for an FHA loan itself, but not yet for the state's help with the down payment, since OHFA's down payment assistance program sets its floor 50 points higher than FHA does on its own.
Can a 600 Credit Score Qualify for Ohio Down Payment Assistance?
Not yet in most cases. OHFA requires a minimum 650 score for FHA-backed assistance and 640 for conventional, USDA, or VA assistance. A 600-score buyer typically needs to raise their score by 40 to 50 points before qualifying for the state's down payment help.
That gap is worth closing before applying, not after. OHFA's assistance covers 3% to 3.5% of the purchase price toward a down payment or closing costs, and the funds are forgiven after seven years of staying in the home. On a Columbus-priced house near $300,000, that assistance can run close to $10,000, money a 600-score buyer would otherwise have to bring to closing out of pocket.
Qualifies for a 3.5% down FHA loan but has to fund the entire down payment independently, since OHFA assistance is out of reach until the score climbs.
Same FHA loan, but now paired with up to 3.5% in forgivable down payment assistance from the state, cutting the cash needed at closing significantly.
How Much Does a 600 Credit Score Cost You on a Columbus Mortgage?
A lower score means a higher interest rate on the same loan amount, which adds up over 30 years. The gap between a 600-score FHA rate and a 740-score conventional rate on a Columbus-priced home can amount to tens of thousands of dollars in extra interest over the life of the loan.
ASAP's own analysis of what credit score is needed for a $400,000 house found that the interest gap between a 620-tier borrower and a 740-tier borrower can run into six figures over a full loan term. Columbus homes carry a lower median price than that example, but the rate mechanics work identically at $299,802, and the underlying pattern holds at any price point.
What Should a 600-Score Buyer Do Before Applying?
Focus on the moves that raise a score fastest: lowering credit card balances, correcting reporting errors, and avoiding new credit inquiries in the months before applying. Even a modest climb can shift rate pricing or unlock OHFA's assistance program.
ASAP's guide on getting an FHA loan with a low credit score lays out the specific levers that matter most for a borrower sitting near the FHA floor, and the same guide on going from a 500 to a 700 credit score breaks the climb into a realistic 12 to 24 month timeline.
- ✓ Pull a full credit report and dispute any inaccurate or unverifiable accounts
- ✓ Pay down revolving balances toward 30% of each limit, ideally lower
- ✓ Avoid opening new credit accounts or closing old ones before applying
- ✓ Keep every account current for at least 12 months before applying, if possible
- ✓ Ask an FHA lender for a rate quote at your current score, then again after 60 to 90 days of cleanup
See What's Standing Between You and a 650
A free 3-bureau audit shows exactly what's holding your score at 600, including errors that may be dragging it down without you knowing.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Is the Columbus Housing Market Like Right Now for a First-Time Buyer?
Columbus's median home sale price is $299,802 as of August 2026, up modestly year over year, with homes selling in a median of 42 days. Prices remain well below the national median, making Columbus one of the more accessible major metros for a buyer working with a 600 credit score.
A sub-$300,000 median price changes the math for a 600-score buyer in a real way. A smaller loan amount means a smaller monthly gap between rate tiers, and it means the OHFA assistance figure, calculated as a percentage of purchase price, stretches further than it would in a pricier metro.
A 600 credit score is enough to buy a house in Columbus through an FHA loan, but it sits just below the threshold for the state's own down payment assistance and well below conventional loan minimums. Closing that gap, even partially, changes both the rate offered and the amount of cash needed at closing. In a market priced near $300,000 with homes moving in about six weeks, that gap is worth closing before house hunting starts in earnest.
Can you buy a house in Columbus with a 600 credit score?
Yes. A 600 credit score clears the 580 minimum for an FHA loan with 3.5% down. It falls short of most conventional loan minimums, which typically start at 620, so FHA financing is the realistic path for a 600-score buyer in Columbus.
What credit score do you need to buy a house in Ohio?
FHA loans require a minimum 580 score for 3.5% down, or 500 to 579 with 10% down. Conventional loans typically require 620 or higher. Ohio's state down payment assistance program, OHFA, sets its own higher floor of 650 for FHA loans and 640 for conventional, USDA, and VA loans.
Can a 600 credit score qualify for Ohio down payment assistance?
Not yet in most cases. OHFA requires a minimum 650 score for FHA-backed assistance and 640 for conventional, USDA, or VA assistance. A 600-score buyer typically needs to raise their score by 40 to 50 points before qualifying for the state's down payment help.
How much does a 600 credit score cost you on a Columbus mortgage?
A lower score means a higher interest rate on the same loan amount, which adds up over 30 years. The gap between a 600-score FHA rate and a 740-score conventional rate on a Columbus-priced home can amount to tens of thousands of dollars in extra interest over the life of the loan.
What is the Columbus housing market like right now for a first-time buyer?
Columbus's median home sale price is $299,802 as of August 2026, up modestly year over year, with homes selling in a median of 42 days. Prices remain well below the national median, making Columbus one of the more accessible major metros for a buyer working with a 600 credit score.
Turn a 600 Into a Stronger Approval
Get a free, no-obligation credit analysis and a clear plan to raise your score before you apply, backed by a full 3-bureau review.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
What Credit Score Do I Need for a Mortgage? Requirements & Expert Tips The full breakdown of minimum score thresholds across FHA, conventional, and jumbo loan types nationwide.
-
Is 600 a Good Credit Score? Honest Breakdown, Costs & How to Improve Covers what a 600 score qualifies for across loan types, credit cards, and interest rates, beyond just mortgages.
-
Easy Ways On How to Get an FHA Loan with Low Credit Score Walks through the specific steps to strengthen an FHA application when your score sits near the program minimum.
-
What Credit Score Do You Need for a $400,000 House? Compares monthly payment and lifetime interest cost across credit tiers on a comparable loan amount.
-
How to Go From 500 to 700 Credit Score Fast Lays out a realistic 12 to 24 month roadmap for the exact climb a 600-score buyer needs to make.