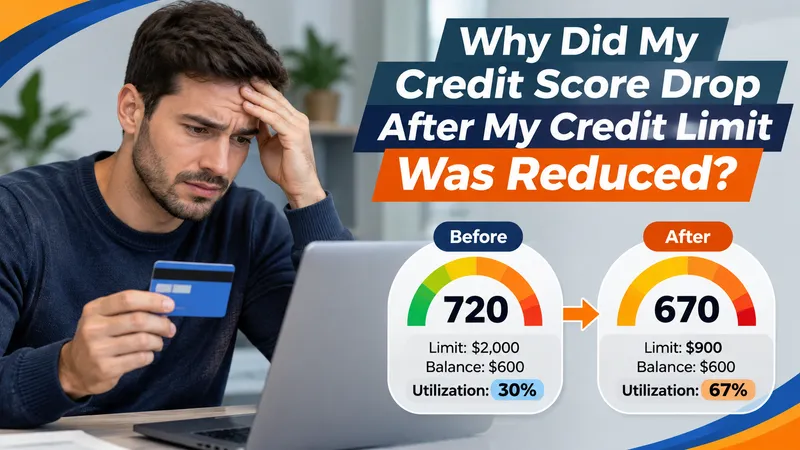
Why did my credit score drop after my credit limit was reduced, even though I never missed a payment? The answer often comes down to credit utilization, which measures how much of your available credit you use. Imagine having a credit card with a $2,000 limit and a $600 balance. You're using 30% of your available credit. If your bank suddenly lowers that limit to $900, your utilization jumps to nearly 67%, even though you haven't spent another dollar. FICO considers amounts owed, including credit utilization, when calculating credit scores. That means a decision made by your credit card issuer can affect your score without any change in your payment habits. For consumers preparing to apply for a mortgage, auto loan, or another credit card, an unexpected score drop can create a frustrating financial setback.
A reduced credit limit doesn't always mean you've done something wrong. Banks may adjust credit limits because of account inactivity, changes in credit history, or internal lending policies. However, inaccurate information on your credit report can sometimes influence these decisions. At ASAP Credit Repair USA, we understand how important it is to identify the actual reason behind a sudden credit score change before taking action. This guide explains why lenders reduce credit limits, how those reductions affect your FICO score, what credit reporting errors to watch for, and the practical steps you can take to improve your credit utilization and recover from a score drop.
Why Does a Credit Limit Reduction Drop Your Credit Score?
A credit limit reduction drops your credit score because it increases your credit utilization ratio, the percentage of your available revolving credit that you are using. Utilization accounts for 30% of FICO 8. When your credit limit is cut, and your balance stays the same, utilization goes up automatically — without you spending a dollar more. FICO calculates utilization both per card and across all revolving accounts combined. A spike on one card damages both calculations.
The math is straightforward and unforgiving. A $600 balance on a $2,000 credit limit is 30% utilization, sitting right at the threshold where FICO begins to register meaningful scoring pressure. If that lender cuts the limit to $900, the same $600 balance is now 67% utilization. Nothing about how you used the card changed. Everything about how the scoring model reads your risk profile changed.
How FICO Calculates Utilization
FICO measures utilization in two ways simultaneously. Per-card utilization looks at each revolving account individually: the balance on a single card divided by that card's credit limit. Aggregate utilization adds up all revolving balances across all cards and divides by all revolving credit limits combined. A limit reduction on one card damages both numbers at the same time. The per-card calculation goes up because that specific card's ratio worsened. The aggregate calculation goes up because total available credit decreased while total balances stayed the same.
Scoring models apply heavier penalties as utilization crosses specific thresholds. The 30% mark is where the first meaningful scoring pressure begins. At 50%, the model registers higher risk. At 75% and above, the utilization factor is working strongly against the score. A limit reduction that pushes a card from 28% to 68% crosses two of those thresholds in a single event; the score impact reflects both crossings at once.
Why the Card Issuer Reduced the Limit
Card issuers conduct periodic account reviews, sometimes every six to twelve months using updated credit bureau data. If the review shows a drop in credit score, new delinquencies on other accounts, a higher overall debt load, or reduced income signals, the issuer may reduce the credit limit as a risk management step. Some reductions happen automatically through scoring algorithms. Others are manually triggered by specific flags in the account profile.
Common triggers for limit reductions include: inactivity on the card for an extended period, a missed payment on a different account with the same issuer, a score drop caused by a new hard inquiry or a balance increase on another card, a lapse in income verification, or broad-based portfolio risk management during economic downturns. Card issuers reduced limits widely during the 2008 financial crisis and again during 2020, affecting borrowers who had done nothing wrong on that specific account.
How Much Can a Credit Limit Reduction Lower Your Credit Score?
A credit limit reduction that pushes a card's utilization from under 30% to above 60% typically drops a credit score between 20 and 50 points. The drop is larger when the affected card represents a large share of total available credit, when the file has fewer open revolving accounts, or when the utilization spike crosses multiple scoring thresholds, particularly the 30%, 50%, and 75% breakpoints where FICO applies progressively heavier score penalties.
The size of the drop depends on three variables: how far utilization moved, how much of the borrower's total available revolving credit the affected card represents, and where the starting score stood. High-score borrowers tend to see larger drops from utilization spikes because their scores had further to fall. Borrowers with already-elevated utilization across multiple cards see less additional damage from one more card's ratio increasing.
| Balance | Limit Before Reduction | Utilization Before | Limit After Reduction | Utilization After | Likely Score Impact |
|---|---|---|---|---|---|
| $500 | $5,000 | 10% | $2,500 | 20% | Minor — still below 30% |
| $500 | $2,500 | 20% | $1,000 | 50% | Moderate — crosses 30% and 50% thresholds |
| $600 | $2,000 | 30% | $900 | 67% | Significant — crosses 50% and 60% thresholds |
| $800 | $2,000 | 40% | $1,000 | 80% | Severe above 75% threshold; maximum scoring pressure |
The good news embedded in these numbers is that utilization damage reverses fast. Scoring models recalculate utilization based on the balances and limits that report during each billing cycle. Pay down the balance, and the score recovers at the next cycle, typically within 30 to 45 days. No other scoring factor responds this quickly. Payment history damage from a missed payment takes seven years to fully age off. A utilization spike from a limit reduction can be reversed in a single billing cycle.
Does the Lender Have to Tell You Why Your Credit Limit Was Reduced?
Yes. Under the Equal Credit Opportunity Act, a lender that reduces your credit limit is required to send an adverse action notice in writing, within 30 days, stating the specific reasons for the action. The notice must name the actual factors used: a drop in credit score, a change in payment behavior on other accounts, inactivity on the card, or an income verification issue. A generic notice that cites only "your credit report" without specific reasons does not meet ECOA requirements.
The adverse action notice requirement exists specifically so that consumers can identify and address the underlying reason for a credit decision. If the reason for your limit reduction was a late payment on your credit report that does not belong there, the adverse action notice tells you that — and that is your starting point for disputing both the inaccurate entry and requesting that the limit be restored.
What the Adverse Action Notice Must Include
An ECOA-compliant adverse action notice states the specific principal reasons for the adverse action, typically up to four factors, ranked by their weight in the decision. Common stated reasons include: "delinquent past or present credit obligations with others," "too many accounts with balances," "too high a proportion of revolving balances to revolving credit limits," "length of time accounts have been established," and "too many inquiries in the last 12 months." The lender is also required to tell you if a credit score was used and, if so, which score, what your score was, the score range, and what factors most affected it.
What to Do If the Stated Reason Is Based on an Error
When the adverse action notice cites a reason that reflects an inaccurate entry on your credit report a late payment you did not miss, a balance shown higher than it actually was, or a derogatory entry that belongs to someone else that inaccuracy becomes a two-front dispute. First, dispute the reporting error with the bureau and the furnisher under FCRA Sections 611 and 623. Second, once the error is corrected, contact the card issuer's reconsideration line, the team specifically designated to review limit reduction decisions, and provide the corrected credit report as evidence that the basis for the reduction was inaccurate. Many issuers will restore the original limit when the triggering inaccuracy is removed from the report.
See What Your Credit Report Shows — Including the Entry That Triggered Your Limit Reduction
A free 3-bureau audit pulls your current Experian, TransUnion, and Equifax reports so you can see exactly which entries the card issuer reviewed — and identify any inaccuracy that may have triggered the limit reduction and the score drop that followed.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card requiredWhat Credit Report Errors Happen After a Credit Limit Reduction?
The most common errors after a credit limit reduction are: the new lower limit not updating on the credit report — leaving the old higher limit in the system until a delayed update suddenly posts and causes a utilization spike; the lender closing the account entirely instead of reducing the limit, which carries different and more severe scoring consequences; and the lender adding an incorrect late payment notation during the same billing cycle as the reduction. Each error is disputable with the lender under FCRA Section 623 and with the bureau under FCRA Section 611.
The reporting errors specific to credit limit reductions fall into two categories: errors in how the new limit is reported, and errors that add new negative marks to the account at the same time as the limit change.
The New Limit Not Updating on the Credit Report
When a lender reduces a credit limit, the update goes to the credit bureaus through the standard monthly reporting cycle. If the lender's system does not send the updated limit data promptly, the credit report continues to show the original higher limit. A borrower checking their score during this window sees no utilization change — the report still shows the old limit. When the update finally posts weeks later, the utilization jumps suddenly even though the actual limit was reduced earlier. This delayed reporting creates a confusing timeline where the score drops well after the limit change, with no apparent trigger from the borrower's perspective.
A credit limit reduction affects only the utilization factor. The account stays open, the payment history continues, and the account keeps contributing to average account age and credit mix. An account closure removes the available credit entirely, also spikes utilization, removes the account from the active mix calculation, and may affect average age of accounts. If your account was closed when you expected only a limit reduction — or if the closed status appeared on the credit report when the account was not supposed to be closed — that is a reporting error with broader scoring damage than a limit reduction alone would produce. It requires an immediate dispute under FCRA Section 623 to have the account status corrected.
Incorrect Late Payment Notation Added During the Limit Change
Some borrowers find a 30-day late payment notation appearing on the account during the same billing cycle as a credit limit reduction. This is a separate and more damaging error. A limit reduction alone does not create any negative payment history. If a late payment appears on the account and you made every payment on time, the late notation is a reporting error that is entirely independent of and more damaging than the utilization impact from the limit change. The payment history factor carries 35% of FICO 8. A single erroneous late notation costs more points than a utilization spike on most files.
The Limit Reported Incorrectly Across Different Bureaus
Lenders report to Experian, TransUnion, and Equifax on independent cycles. It is possible for the reduced limit to update on one bureau while the original limit remains on the others, producing different utilization ratios on different reports. When a lender pulls the bureau that still shows the old limit, utilization looks lower than it actually is. When a lender pulls the bureau that updated the new limit, utilization looks higher. For mortgage applications specifically, lenders typically pull all three and use the middle score. Inconsistent limit reporting across bureaus creates unpredictable score variation depending on which report is used for a given application.
How Do You Recover Your Credit Score After a Credit Limit Reduction?
The fastest recovery is paying down the balance on the affected card. Even a partial paydown that brings utilization back below 30% produces a meaningful score recovery in the next reporting cycle — usually within 30 to 45 days. You can also call the lender's reconsideration line and request that the original limit be restored, especially if the reduction was triggered by an error in the periodic account review. Check the credit report to confirm the new limit is reporting correctly on all three bureaus and that no additional errors were added during the limit change process.
Recovery from a limit reduction score drop has two tracks: fixing the number directly by reducing the balance, and fixing the underlying limit if the reduction was based on inaccurate information. Both can happen simultaneously and both should be pursued in parallel.
- ✓ Calculate your new utilization and identify the target paydown amount. Divide your current balance by the new credit limit to find the current utilization percentage. To bring the card below 30% utilization, you need the balance to be less than 30% of the new limit. To bring it below 10% — the range where utilization adds the most scoring benefit — the target is under 10% of the new limit. Identify the exact dollar amount needed to reach each threshold.
- ✓ Pay down the balance before the next statement closing date. Utilization reports at the statement balance — the balance on the account when the billing cycle closes — not at the balance when payment is due. To get the paydown reflected in next month's credit report, the balance must be reduced before the statement date, not just before the payment date. Check your statement closing date in the card's online account portal.
- ✓ Call the lender's credit limit reconsideration line. Most major card issuers have a reconsideration team separate from general customer service. Request a review of the limit reduction decision. If the adverse action notice cited a credit report entry that you believe is inaccurate, say so and ask the representative to note the dispute in your account record. Even if the reconsideration does not restore the limit immediately, it creates a record and sometimes leads to restoration after a short review period.
- ✓ Pull your credit report and verify the new limit is reporting correctly on all three bureaus. Go to AnnualCreditReport.com and pull Experian, TransUnion, and Equifax. Confirm the credit limit on the affected account matches the actual new limit on all three reports. If any bureau still shows the old limit, it will update on its own — but inconsistent limit data across bureaus creates score variability that can affect applications in the interim.
- ✓ Check whether the adverse action notice cited a credit report error as the reason for the reduction. Review the reason codes on the adverse action notice. If any reason references information that you know to be inaccurate — a delinquency you did not have, a balance shown higher than it was, an account that was not yours — file a dispute with that bureau and furnisher under FCRA Sections 611 and 623. After the error is corrected, provide the corrected report to the card issuer's reconsideration team as evidence for limit restoration.
- ✓ If the reduction was based on a credit report error and the issuer does not restore the limit after correction, file a CFPB complaint. At consumerfinance.gov/complaint, document the sequence: inaccuracy on report, limit reduced citing that report, inaccuracy corrected, issuer declined restoration. The CFPB contacts the issuer and requires a formal written response. This level of documentation creates regulatory pressure that reconsideration calls alone do not.
- ✗ Do not close other credit cards in response to the limit reduction. Closing other cards reduces total available revolving credit further, which raises aggregate utilization even more. It also removes open accounts from the mix calculation and potentially lowers average account age. The scoring math is straightforward: closing cards after a limit reduction makes utilization worse, not better.
- ✗ Do not apply for new cards immediately after the score drops. A new card application generates a hard inquiry, which causes a small additional score drop. More significantly, applying for new credit while utilization is high signals to the scoring model that you are seeking additional credit under financial pressure — which some models penalize separately from the utilization factor. Wait until utilization is back below 30% on all cards before applying for new credit.
A credit limit reduction damages your score through one mechanism: it increases your credit utilization ratio, which carries 30% of FICO 8. The damage reverses faster than almost any other scoring injury — a balance paydown that brings utilization below 30% reflects in the score within one billing cycle. If the reduction was based on an inaccurate credit report entry, disputing the entry and requesting reconsideration from the issuer can restore both the limit and the score. The adverse action notice is your roadmap: it tells you exactly which factors and which bureau report the issuer used to make the decision.
Why does a credit limit reduction drop your credit score?
A credit limit reduction drops your credit score because it increases your credit utilization ratio — the percentage of your available revolving credit that you are using. Utilization accounts for 30% of FICO 8. When your credit limit is cut and your balance stays the same, utilization goes up automatically without you spending a dollar more. FICO calculates utilization both per card and across all revolving accounts combined. A spike on one card damages both calculations.
How much can a credit limit reduction lower your credit score?
A credit limit reduction that pushes a card's utilization from under 30% to above 60% typically drops a credit score between 20 and 50 points. The drop is larger when the affected card represents a large share of total available credit, when the file has fewer open revolving accounts, or when the utilization spike crosses multiple scoring thresholds — particularly the 30%, 50%, and 75% breakpoints where FICO applies progressively heavier score penalties.
Does the lender have to tell you why your credit limit was reduced?
Yes. Under the Equal Credit Opportunity Act, a lender that reduces your credit limit is required to send an adverse action notice in writing within 30 days stating the specific reasons for the action. The notice must name the actual factors used: a drop in credit score, a change in payment behavior on other accounts, inactivity on the card, or an income verification issue. A generic notice that cites only "your credit report" without specific reasons does not meet ECOA requirements. If you did not receive a proper adverse action notice, file a complaint with the Consumer Financial Protection Bureau.
What credit report errors happen after a credit limit reduction?
The most common errors after a credit limit reduction are: the new lower limit not updating on the credit report, leaving the old higher limit in the system and masking the utilization spike until the update suddenly posts weeks later; the lender closing the account entirely instead of reducing the limit, which carries different and more severe scoring consequences; and the lender adding an incorrect late payment notation during the same billing cycle as the reduction. Each error is disputable with the lender under FCRA Section 623 and with the bureau under FCRA Section 611.
How do you recover your credit score after a credit limit reduction?
The fastest recovery is paying down the balance on the affected card. Even a partial paydown that brings utilization back below 30% produces a meaningful score recovery in the next reporting cycle — usually within 30 to 45 days. You can also call the lender's reconsideration line and request that the original limit be restored, especially if the reduction was triggered by an error in the periodic account review. Check the credit report to confirm the new limit is reporting correctly on all three bureaus and that no additional errors were added during the limit change process.
Find Out Which Credit Report Entry Triggered Your Limit Reduction — and Whether It's Accurate
A free 3-bureau audit reviews your Experian, TransUnion, and Equifax reports so you can identify the entry the card issuer flagged in its periodic review — and determine whether the limit reduction was based on accurate data or on an error that can be corrected and disputed.
Claim My Free Credit Analysis Now → Secure · 2 minutes · No credit card required-
Capital One Closed My Account Without Warning: Will It Hurt My Credit? Account closure carries all the scoring damage of a limit reduction — plus the loss of available credit, an average age impact, and a potential credit mix effect. Covers how to dispute an inaccurate closed status and minimize the damage.
-
Why Did My Credit Score Drop After Paying Off My Car Loan? Another counterintuitive score drop — a positive financial action producing a negative scoring result. Covers credit mix loss, average age shifts, and the reporting errors that make the drop larger than it should be.
-
How to Dispute Credit Report Errors: A Step-by-Step Guide The complete FCRA dispute process — what to include, what the bureaus are required to do, and what happens when a dispute is rejected or the error is not corrected.