Rupp & Associates sent you a collection letter. Before you pay it, trace the amount back to the account that created the debt.
Rupp & Associates is a debt collection agency based in Timonium, Maryland. The company says it handles consumer debts across many industries, with a high concentration in property management.
That makes the records behind the letter important. If the debt came from a former apartment, for example, the balance could involve rent, fees, damage charges, a security deposit, payments, or other adjustments.
Errors and disputed debts are not rare in the wider collection market. In the CFPB's 2025 FDCPA report, 45% of debt collection complaints filed in 2024 involved attempts to collect debts consumers said they did not owe. Another 31% involved written notices about debts.
A collection letter should therefore be treated as the start of your review, not the end of it.
Each debt collector client experience has shown us why it helps to separate the collector from the account behind the collection. You can recognize the creditor but disagree with the amount. Or you may recognize the balance but find that a payment or credit is missing.
This guide shows you how to trace a Rupp & Associates collection letter back to the creditor. The account records, charges, payments, and credits before deciding whether to pay, dispute, or ask for more information.
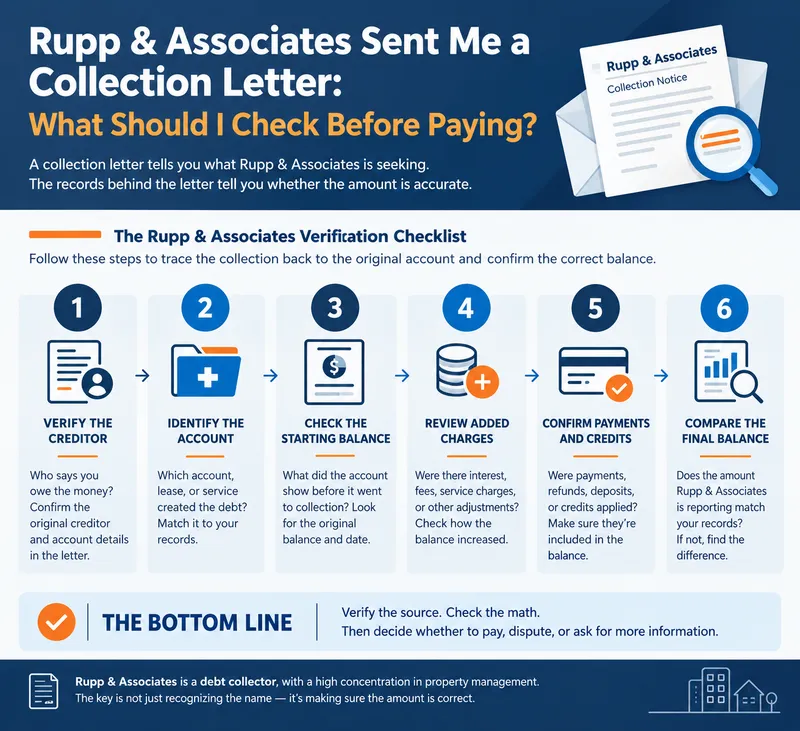
Rupp & Associates Sent Me a Collection Letter: What Should I Check Before Paying?
If Rupp & Associates sends you a collection letter, check the creditor, account number, original transaction, starting balance, added charges, payments, credits, and current amount before paying. If the debt involves a former apartment, also compare the letter against your lease, move-out statement, security deposit, and any rent or damage charges.
Rupp & Associates sent you a collection letter. Before paying, trace the amount back to the account that created the debt. It's a debt collection agency in Timonium, Maryland, operating since 1982, with a stated concentration in property management - so a former apartment is one plausible source, not the only one.
The records behind the letter are the real subject here. A former apartment balance often layers rent, fees, damage charges, a deposit, and payments together. Errors aren't rare in the broader market: the CFPB's 2025 FDCPA report found collecting a debt the consumer said wasn't owed was the single most common complaint issue in 2024.
Nearly 20 years of credit repair work at ASAP Credit Repair has shown us why separating the collector from the account matters - one person recognizes the creditor but disagrees with the amount, another finds a payment missing. This guide traces the letter to the creditor, records, and credits before you pay, dispute, or ask for more information.
Key Takeaways
- Rupp & Associates is a Maryland debt collector with a stated concentration in property management.
- Match the letter to the creditor and account before paying.
- CFPB data shows disputes over whether a debt is owed are a leading complaint driver.
- If the amount doesn't match your records, find the exact difference first.
What Is Rupp & Associates?
Rupp & Associates is a debt collection agency in Timonium, Maryland, handling debt "for all industries with a high concentration in property management" since 1982, with a stated BBB A+ rating and ACA membership.
Is Rupp & Associates a debt collector?
Yes - its site identifies it as a debt collector with the required disclosure.
Is Rupp & Associates a law firm?
No. Its services page lists in-house legal counsel, but describes the business as a collection agency. A letter isn't the same thing as a lawsuit or summons.
Why Did Rupp & Associates Send Me a Letter?
A Rupp letter generally means it's attempting to collect a debt tied to one of its clients. The creditor and account information identifies where it started. Rupp's stated concentration in property management makes a former apartment one plausible source - confirm against your records.
The Rupp Letter-to-Ledger Audit
A collection letter states what Rupp & Associates is seeking. The ledger behind it shows whether the amount reconciles. Run it through this audit and stop at the first broken link:
Is Rupp & Associates Showing on Your Credit Report?
Check whether the creditor, balance, and account details are accurate. Our team reviews reports and flags what needs attention.
Get My Free Credit Analysis Now →What Must Be in the Collection Notice?
Under Regulation F, validation information generally includes the collector and consumer's information, the current creditor, the account number, the itemization date and amount, interest, fees, payments, credits, the current amount, and dispute instructions.
Why the Ledger Matters More Than the Letter Alone
A notice summarizes a claim; a ledger shows the work.
| Component | Effect on Balance |
|---|---|
| Beginning balance | Starting point |
| + New charges | Increases the amount |
| + Permitted interest / fees | Increases the amount |
| − Payments | Reduces the amount |
| − Deposits / credits | Reduces the amount |
| = Amount sent to collections | Should equal Rupp's stated balance |
That gap is the dispute.
If the Letter Is About a Former Apartment
Rupp & Associates states a high concentration in property management, so rental debt gets its own check.
- Monthly rent, lease dates, and move-out date
- Early-termination clause and any concessions, and whether repayment was required
- Fees and deposit terms
- The final move-out statement, compared against the ledger
- Whether the deposit was credited before collection
Treat "apartment debt" as more than one number: rent, fees, and damages minus the deposit should equal the final balance.
A Real-World Pattern: Balance Higher Than the Last Bill
This confusion shows up in consumer forums. In one myFICO thread, a poster questioned how an apartment account a few months past due grew into a far larger balance - a reply explained stacked fees: insufficient-funds charges, late fees, cleaning, and an early-termination charge. A separate account described a move-out bill sent to collections years later, with no prior notice. Neither is authority on Rupp specifically - both show why the ledger, not the letter, is the first move.
What If I Don't Recognize the Creditor?
An unfamiliar name doesn't automatically mean the collection is invalid. Match it to the address, account number, service, or transaction date in your records first. A validation notice sometimes lists more than one creditor, and a process exists for requesting original-creditor details.
What If the Amount Is Higher Than My Last Bill?
Compare the itemization date and starting balance against interest, fees, payments, and credits since then. The amount should trace through those changes.
| Record | Your Records | Collection Notice | Match? |
|---|---|---|---|
| Starting balance | ____ | ____ | Yes / No |
| Rent / service charges | ____ | ____ | Yes / No |
| Damage charges | ____ | ____ | Yes / No |
| Fees / interest | ____ | ____ | Yes / No |
| Payments | ____ | ____ | Yes / No |
| Deposit / credits | ____ | ____ | Yes / No |
| Final balance | ____ | ____ | Yes / No |
What If I Already Paid the Debt?
Among CFPB complaints about debts consumers say they don't owe, 60% said the debt wasn't theirs, 28% cited identity theft, and 10% said it was already paid. Gather your receipt or settlement agreement and match the date and amount against the account.
"Rupp has 30 days to prove the debt before doing anything else."
The collector provides validation at first contact or within 5 days. The 30 days is the consumer's window to dispute - not a waiting period before the collector responds.
Does a Letter Mean It's on My Credit Report?
No. A letter and credit reporting are separate events. Under Regulation F, a collector must communicate with the consumer before furnishing a debt to a reporting agency. Check your own reports rather than assuming.
Is This Letter the Same as a Lawsuit?
No. A letter is a demand or communication about a debt. A lawsuit involves court-filed documents and a timed response. In-house legal counsel doesn't make every account a lawsuit - a letter and a summons are different stages.
Should I Pay Rupp & Associates?
| What You Find | Better First Step |
|---|---|
| Creditor and balance match | Review payment options |
| Debt isn't yours | Document and dispute |
| Creditor is unfamiliar | Trace the underlying account |
| Balance differs | Reconcile the ledger |
| Payment is missing | Gather payment proof |
| Security deposit missing | Compare move-out records |
| Damage charge disputed | Check the lease and documentation |
| Court papers received | Address the court deadline directly |
The Rupp & Associates Letter-to-Ledger Worksheet
| Verification Point | Rupp Letter | Source Record | Match? |
|---|---|---|---|
| Creditor | ____ | ____ | Yes / No |
| Account number | ____ | ____ | Yes / No |
| Property / provider | ____ | ____ | Yes / No |
| Starting balance | ____ | ____ | Yes / No |
| Rent / service charges | ____ | ____ | Yes / No |
| Security deposit / credits | ____ | ____ | Yes / No |
| Final balance | ____ | ____ | Yes / No |
Stop at the first "No." That's the relationship needing clarification.
Separate the Collector From the Account
Nearly 20 years of credit repair work at ASAP Credit Repair has shown us collection problems are easier to resolve once each part of the chain is reviewed on its own - the collector, creditor, ledger, and report entry each answer a different question. Start with records, not assumptions.
Found a Discrepancy in the Ledger?
If the balance doesn't reconcile, or the report entry doesn't match what you verified, our team helps identify what warrants action.
Get My Free Credit Analysis Now →Frequently Asked Questions
Who is Rupp & Associates?
Rupp & Associates is a consumer debt collection agency based in Timonium, Maryland, operating since 1982 across industries, with a high concentration in property management.
Why did Rupp & Associates send me a collection letter?
A Rupp & Associates letter generally means the company is attempting to collect a debt tied to one of its clients. The creditor and account information identifies where it originated - trace it back before paying.
Is Rupp & Associates a debt collector?
Yes. Its own website identifies it as a debt collector and includes the required disclosure.
Is Rupp & Associates a law firm?
No. Its site lists in-house legal counsel, but describes itself as a collection agency, not a law firm.
Does Rupp & Associates collect apartment debt?
Rupp & Associates states it handles debt collections for all industries with a high concentration in property management. A former apartment account is one likely source, but not every letter involves rental debt.
What should I check before paying Rupp & Associates?
Check the creditor, account number, original transaction, starting balance, charges, payments, and credits. If it's a former apartment, compare the letter against your lease, move-out statement, and deposit.
What if I don't recognize the creditor Rupp & Associates named?
An unfamiliar name doesn't automatically mean the collection is invalid. Match it to the address, account number, service, lease, or transaction date in your records before disputing.
What if the Rupp & Associates balance is wrong?
Compare the itemization date and starting balance against interest, fees, payments, and credits since that date. Document the exact line that doesn't trace through.
What if I already paid the debt?
Gather your bank statement, receipt, or settlement agreement. Match the payment date, amount, and recipient against the account, then submit that in writing.
What if my security deposit wasn't credited?
Request the final move-out statement and confirm whether the deposit was credited before collection. A missing credit is a specific, documentable discrepancy.
Can I dispute a Rupp & Associates collection?
Yes. Submit a written dispute naming the specific discrepancy within the validation period. If it's on your credit report, dispute that detail separately with the bureau reporting it.
How long do I have to dispute the debt?
Federal rules provide 30 days after you receive, or are assumed to receive, the validation information. A qualifying written dispute pauses collection of the disputed amount until the collector responds.
Does Rupp & Associates have 30 days to validate the debt?
Not exactly. The 30 days belongs to the consumer's dispute window, not a deadline for the collector to prove the debt upfront. The collector must provide validation information at first contact or within five days of it.
Does a collection letter mean the debt is on my credit report?
No. A letter and credit reporting are separate events. A collector must communicate with the consumer before furnishing a debt to a reporting agency - check your own reports.
Is a Rupp & Associates collection letter the same as a lawsuit?
No. A letter is a demand or communication about a debt. A lawsuit involves court-filed documents requiring a separate, timed response. In-house legal counsel doesn't make every account a lawsuit.
Should I pay Rupp & Associates?
Only once the creditor, account, and balance are verified against your own records. What that finds determines the next step, not a blanket yes or no.
Related Reads
- CFPB - 2025 Fair Debt Collection Practices Act Annual Report
- CFPB - What is a debt collection validation notice?
- CFPB - What is a debt validation letter?
- CFPB Regulation F - 12 CFR 1006.30, furnishing information to consumer reporting agencies
- myFICO forum - old apartment debt discussion, search-intent reference only
- JustAnswer - landlord collection account discussion, search-intent reference only